
Blogs
PW Consulting: Global Rheology Modifier Coating Additive Market to Hit $4.79 Billion by 2032 at 4.8% CAGR
By pmarketresearch, 2026-09-17
Strategic Intelligence in the Global Rheology Modifier Coating Additive Market: Key Insights for 2026 Decision-Makers
The global landscape for rheology modifier coating additives is undergoing a structural transformation driven by regulatory shifts, raw material volatility, and the accelerating transition to waterborne formulations. For executives navigating product portfolios, supply chain strategies, and capital allocation in 2026, surface-level market summaries are no longer sufficient. Comprehensive, granular intelligence is required to anticipate margin compression, identify high-growth application pockets, and benchmark competitive positioning against incumbents expanding capacity and launching next-generation chemistries. This newly released Worldwide Rheology Modifier Coating Additive Market study delivers precisely that depth. Designed as a decision-ready intelligence asset, the report synthesizes historical performance, forecast trajectories, and competitive dynamics into a cohesive framework that aligns with the strategic planning cycles of coatings manufacturers, additive suppliers, and downstream formulators.
Market Trajectory and the 2026 Inflection Point
The sector has demonstrated consistent expansion across the historical review window, advancing from approximately 2.75 billion USD in 2020 to an estimated 3.45 billion USD by 2025. This growth reflects sustained formulation modernization across architectural, industrial, and protective coating segments, alongside tightening environmental mandates that favor rheology additives capable of maintaining application performance while reducing volatile organic compound content. Looking ahead, the forecast period from 2026 through 2032 projects a compound annual growth rate of 4.8 percent, positioning the market to surpass 4.79 billion USD by the terminal forecast year.
These aggregated figures represent more than a simple top-line projection. They encapsulate a market recalibrating around formulation efficiency, regulatory compliance, and regional manufacturing footprints. The trajectory indicates that demand will not be distributed uniformly; rather, it will concentrate in applications where viscosity control, sag resistance, and levelness are non-negotiable performance parameters. Understanding how these macro trends intersect with segment-specific drivers, supply chain constraints, and pricing mechanisms is critical for 2026 planning. The full report dissects these intersections without oversimplifying, enabling stakeholders to map growth vectors against their own product roadmaps and procurement strategies.
Executives should note that the forecast horizon extends beyond short-term cyclical fluctuations. The modeled expansion incorporates structural shifts in formulation preferences, regulatory compliance costs, and capacity adjustments by key producers. By grounding strategy in these forward-looking parameters, organizations can better align inventory planning, R&D focus, and partnership development with the market's actual growth architecture. The report provides the analytical scaffolding required to translate these projections into actionable commercial and operational decisions.
Competitive Architecture and Strategic Positioning
The rheology modifier coating additive sector is characterized by a moderately concentrated competitive landscape, with the top three players collectively commanding 38.4 percent of market revenue and the top five accounting for 52.15 percent. This concentration reflects decades of formulation expertise, established technical service networks, and continuous innovation in associative thickeners, organoclays, cellulose derivatives, and polyurethane-based modifiers. Yet the remaining share distribution underscores meaningful fragmentation at the regional and application-specific level, creating both competitive threats and partnership opportunities for incumbents and challengers alike.
Worldwide Rheology Modifier Coating Additive Market
Leading global suppliers have built differentiated value propositions around viscosity control mechanisms, compatibility with low-VOC and solventborne systems, and rapid technical support for formulators. Major players headquartered across North America, Europe, and Asia maintain extensive portfolios spanning organoclays, hydrophobically modified ethoxylated urethanes, polyamide waxes, fumed silica-based additives, and cellulosic thickeners. Their product architectures are increasingly tailored to meet application-specific demands in architectural paints, industrial coatings, automotive finishes, wood and furniture coatings, and marine protective systems. The report profiles these core companies in detail, mapping their product ranges, geographic reach, formulation specialties, and recent strategic moves that signal where each competitor is placing its commercial bets.
Rheology Modifiers Market
Recent corporate activities illustrate the pace of competitive maneuvering. In late 2025, a global leader in organoclay and associative thickeners introduced a VOC-free organoclay rheology modifier engineered for enhanced sag resistance in waterborne coatings, directly addressing the formulation constraints of decorators and industrial painters. Earlier in the same year, a major North American chemical supplier launched a hydrophobically modified alkali-swellable emulsion grade designed to deliver high-shear viscosity in low-VOC paints, reflecting the industry's push for application robustness without compromising environmental performance. Alongside these product launches, certification milestones and production expansions have reshaped the competitive baseline. A prominent European supplier secured EU Ecolabel certification for a polyurethane-based rheovis modifier tailored to low-emission interior coatings, reinforcing its positioning in sustainability-driven architectural segments. Meanwhile, capacity expansions at European manufacturing sites have increased output of specific associative thickeners by roughly 20 percent, underscoring the strategic importance of securing supply for waterborne formulation growth.
These developments are not isolated product news; they are indicators of where value creation is shifting. The report analyzes how each competitive action influences pricing power, formulation substitution risks, and regional supply dynamics. By benchmarking your organization's capabilities against these moves, you can identify gaps in technical service, formulation support, or portfolio coverage that may affect win rates in key customer segments.
Regulatory Currents and Raw Material Dynamics Shaping Formulation Economics
The 2026 planning environment is heavily influenced by regulatory and input-cost variables that directly affect formulation economics and additive selection. Recent regulatory updates have introduced compliance considerations that formulators and suppliers must navigate carefully. Restrictions under EU chemical regulations now limit certain associative thickeners containing nonylphenol ethoxylates above threshold concentrations, prompting reformulation efforts and supplier qualification updates across European and export-oriented markets. In parallel, regional hazard communication requirements in the United States have mandated warning labels for specific thickener chemistries containing unreacted acrylamide, affecting labeling, documentation, and customer communication workflows for decorative and industrial coating producers.
Raw material pricing volatility adds another layer of complexity. Key solvent inputs used in solventborne rheology modifier formulations have experienced notable price fluctuations, with certain glycol ether acetate derivatives averaging elevated levels in late 2025. Simultaneously, isobutanol feedstock costs rose significantly year-over-year due to supply disruptions in the US Midwest, affecting the cost base for certain associative thickener and wax-based systems. These input dynamics do not impact all chemistries equally, which is why understanding the cost structure and substitution elasticity across organic and inorganic rheology modifiers is essential for margin protection.
Trade policy developments further complicate the procurement landscape. Adjustments to US tariff schedules on imported cellulose ethers have increased duty burdens on certain raw material streams, altering the relative cost competitiveness of regional supply chains. For formulators balancing performance, regulatory compliance, and total cost of ownership, these shifts create both risk and opportunity. The report evaluates how regulatory timelines, feedstock price trajectories, and trade measures intersect with segment demand, helping stakeholders anticipate formulation pivots, supplier transitions, and pricing negotiations in 2026 and beyond.
Application-Level Demand Drivers and Formulation Priorities
Demand for rheology modifiers is not uniform across end-use categories. Architectural coatings continue to represent a substantial share of consumption, driven by renovation cycles, housing activity, and the ongoing shift toward waterborne decorative formulations that require precise viscosity control, open time management, and sag resistance. Industrial coatings contribute a significant and technically demanding demand base, where shear-thinning behavior, anti-sag performance, and compatibility with high-solids systems are critical for achieving consistent film formation across metal, plastic, and composite substrates. Automotive coatings impose stringent aesthetic and performance requirements, with rheology additives playing a crucial role in gloss uniformity, levelness, and application robustness under varying shop conditions.
Wood and furniture coatings, as well as marine and protective coatings, represent additional demand pillars with distinct formulation challenges. These segments often require additives that can withstand harsh environmental exposure, maintain stability in solventborne and high-solids systems, and deliver consistent rheological performance across diverse pigment and filler loadings. The report examines how application-specific performance expectations shape additive selection, technical service requirements, and pricing dynamics, highlighting where formulation innovation is translating into commercial differentiation.
Importantly, the growth in waterborne and low-VOC systems is reshaping the relative attractiveness of organic versus inorganic rheology modifiers. Associative thickeners, hydrophobically modified polymers, and advanced cellulosic systems are gaining prominence in segments where environmental compliance and application performance must be balanced. Inorganic thickeners, including organoclays and fumed silica, continue to serve critical roles in solventborne and high-solids applications where thixotropic control and anti-sag properties are paramount. The full analysis delineates how these chemistry preferences evolve across regions and applications, providing a clear view of where substitution risk and portfolio expansion opportunities are most pronounced.
What the Report Delivers: Operational Intelligence for 2026 Planning
This market study is structured to move beyond high-level summaries and deliver operational intelligence that can be immediately integrated into strategy, procurement, and R&D processes. The report provides a comprehensive segmentation framework that maps market size, growth trajectories, and competitive intensity across region, type, and application dimensions. Stakeholders gain visibility into where demand is consolidating, where regional manufacturing footprints influence supply security, and which application categories are driving the most technically advanced rheology modifier requirements.
The competitive profiling section delivers detailed assessments of leading suppliers, including their headquarters, core product families, formulation specialties, and strategic positioning within architectural, industrial, automotive, wood, and marine coating markets. These profiles are complemented by a timeline of recent corporate developments, including product launches, grade introductions, capacity expansions, and certification achievements. By connecting these actions to broader market trends, the report helps readers interpret competitor intent and anticipate shifts in technical service emphasis, portfolio focus, and regional availability.
Beyond competitive and segmentation analysis, the study integrates market concentration metrics to clarify the balance between incumbent dominance and niche competition. This context is essential for assessing pricing dynamics, negotiating leverage, and the feasibility of entering or expanding within specific sub-segments. The report also examines how regulatory timelines, raw material cost movements, and trade policy adjustments are affecting formulation economics, providing a practical lens for evaluating supplier alternatives, inventory strategies, and cost pass-through mechanisms.
For organizations seeking to align product development with market demand, the report outlines the performance parameters that increasingly drive additive selection, including viscosity buildup characteristics, shear-thinning behavior, compatibility with waterborne and solventborne systems, and compliance with evolving environmental standards. These insights are designed to inform technical service roadmaps, customer messaging, and cross-functional planning across R&D, sales, and supply chain teams. By consolidating market sizing, competitive intelligence, regulatory context, and application-level demand drivers into a single authoritative source, the study reduces the time and uncertainty associated with piecing together fragmented data from multiple channels.
Translating Market Intelligence into 2026 Action
The strategic value of this report lies in its ability to convert complex market signals into clear decision frameworks. For coatings manufacturers, the analysis supports formulation portfolio optimization, raw material sourcing strategies, and regional expansion priorities. For additive suppliers, the study provides a detailed view of competitor positioning, customer formulation trends, and capacity allocation signals that inform technical service investments and product launch timing. For downstream stakeholders and investors, the report offers a structured perspective on market concentration, growth vectors, and the regulatory and cost variables that will shape profitability through the end of the decade.
In a market where performance expectations are rising, regulatory compliance is intensifying, and raw material costs are subject to regional disruptions, information advantage translates directly into commercial resilience. The report is designed to deliver that advantage by providing granular, decision-grade intelligence that goes well beyond aggregated headline figures. Stakeholders who integrate these insights into their 2026 planning cycles will be better positioned to navigate formulation transitions, manage supply chain volatility, and capture growth in the segments where rheology modifiers are becoming increasingly indispensable.
To access the complete segmentation analysis, full competitor profiles, detailed regional and application breakdowns, and the comprehensive regulatory and raw material assessments that underpin the forecast model, please visit the source page for the Worldwide Rheology Modifier Coating Additive Market research. The full report provides the depth and precision required to turn market intelligence into executable strategy across 2026 and the forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Rheology Modifier Coating Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Portable Gantry Crane Market Hits $682.57M in 2025, Projected 4.71% CAGR Through 2032
By pmarketresearch, 2026-09-17
Powering Precision: Strategic Imperatives in the Global Portable Gantry Crane Market Through 2032
The worldwide portable gantry crane market stands at a critical inflection point where operational flexibility, material science, and automation converge to redefine how industries move heavy loads. As manufacturing footprints shift, warehouse networks expand, and construction programs demand faster mobilization, portable gantry cranes have transitioned from utilitarian support equipment to strategic assets that shape throughput, safety, and capital efficiency. For executives navigating a 2026 decision cycle, understanding where this market is headed—and why—is no longer optional. The latest market intelligence from PW Consulting maps a seven-year trajectory of steady expansion, structural segmentation, and intensifying competitive differentiation, offering a decision-grade lens for procurement, product strategy, and regional deployment.
This analysis is designed as a strategic preview of our full market study. It surfaces the macro architecture of demand, the forces reshaping supply, and the operational questions that will determine which organizations capture value as the market matures. The objective is to equip leadership teams with a clear framework for interpreting growth, evaluating vendor portfolios, and anticipating the material and regulatory variables that will influence total cost of ownership in the years ahead.
Worldwide Spider Crane Market
Market Architecture and the Growth Trajectory
Drawing on historical performance from 2020 through 2025 and a forward view extending to 2032, the market demonstrates resilient expansion anchored in broad-based industrial demand. The overall revenue base has progressed from approximately 545.12 million USD in 2020 to 682.57 million USD in 2025, reflecting cumulative growth across multiple end-use sectors and geographies. The forecast period maps a continued ascent, with 2026 projecting to 735.99 million USD, followed by measured climbs through the late 2020s and acceleration into the early 2030s, reaching an estimated 942.03 million USD by 2032. This path implies a compound annual growth rate of 4.71 percent over the forecast horizon, a pace that signals durable demand rather than cyclical spikes.
Such a growth profile is meaningful for capital planning. A mid-single-digit CAGR in a specialized lifting equipment category suggests that the market is being pulled by structural enablers—modular facility design, just-in-time material flow, and the need for rapidly deployable lifting solutions—rather than by a single short-term catalyst. The base year of 2025 and the historical window provide a validated reference point, while the forecast interval gives executive teams a usable planning runway for product roadmaps, capacity allocation, and service infrastructure. In practical terms, the numbers indicate that demand will keep expanding, but the distribution of that growth will vary by segment, region, and application profile, making segmentation intelligence essential for targeted investment.
Segmentation Signals That Shape Strategy
Portable gantry cranes are not a uniform category. Demand fractures along material construction, lifting capacity, end-user industry, and regional operating environment, and each fracture point carries distinct implications for pricing, specification, and service requirements.
- Material choice remains a defining commercial variable. Steel-based portable gantry cranes represent the larger revenue pool, favored where structural robustness, higher load retention, and long service life are paramount. Aluminum portable gantry cranes form a substantial secondary stream, appealing where portability, corrosion resistance, and rapid reconfiguration matter most. The balance between these material paths is sensitive to input cost dynamics, and in 2025 global steel prices stabilized in the low-to-mid $800s per short ton in the United States, with sideways to modestly firmer trends anticipated into 2026 as iron ore and scrap costs continue to influence producer economics. In parallel, the Chinese benchmark steel price reached approximately 3,154 CNY per ton as of April 2026, reflecting a moderate year-over-year uptick of about 2.57 percent.
- Capacity requirements divide the market into three practical bands: below 1 ton, 1 to 5 tons, and above 5 tons. Each band aligns with a different operational profile, from light industrial and workshop lifting to mid-range warehouse handling and heavier construction or infrastructure support. Understanding which capacity band is gaining share—and where—helps buyers and manufacturers align product portfolios with real-world load profiles rather than nominal specifications.
- End-user demand spans automotive and transportation, warehousing and logistics, construction and infrastructure, and general manufacturing. Each vertical imposes different cadence, duty cycle, and safety expectations. Warehousing and logistics often prioritize quick setup and repeatable lift precision; construction and infrastructure favor mobility and ruggedness; automotive and transportation applications demand consistency across line-side handling; and general manufacturing seeks adaptable solutions that can serve multiple work cells.
- Regional variation matters as much as application variation. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each region exhibiting its own mix of infrastructure spend, industrial modernization, and procurement norms. The regional split is not merely a geographic footnote; it reflects divergent adoption curves for automation, differing labor cost structures, and local content expectations that influence both specification and sourcing strategy.
These segmentation layers interact. A steel crane in the 1-to-5-ton band may be the right answer for a construction staging yard, while an aluminum unit in the same capacity range may fit a cross-dock logistics operation better. The strategic value of segmentation insight is that it converts a broad market number into actionable selection criteria for both buyers and vendors.
Competitive Landscape and Differentiation Levers
The market is characterized by a broad manufacturer base with a concentration profile that signals room for competitive maneuvering. The combined share of the top three participants stands at 18.45 percent, and the top five reach 29.12 percent, indicating a fragmented landscape where product specialization, regional reach, and service capability can outweigh scale alone. This structure rewards companies that can combine reliable mechanical design with application-specific configurations and responsive support.
Several established players illustrate the differentiation pathways shaping the market. Spanco, Inc. focuses on portable gantry cranes with adjustable height, span, and tread options across steel and aluminum lines, emphasizing flexible industrial material handling. Wallace Cranes designs portable gantry systems and broader industrial crane platforms for manufacturing, construction, and warehouse use, with a clear alignment to OSHA safety expectations. Shuttlelift targets heavy-duty lifting of long and oversized loads through rubber-tired mobile gantry cranes, including series engineered for concrete, steel, and modular components. Konecranes contributes mobile and portable gantry options with advanced automation, safety features, and precise control systems. Liebherr brings hydraulic sophistication and heavy-duty performance to gantry and mobile crane offerings, particularly in construction and industrial settings. Gorbel emphasizes easy-to-install portable gantry designs for job sites that require quick setup and adaptability in constrained spaces. Vestil Manufacturing Corp. supplies fixed-height portable gantry solutions for work-area lifting, with capacities geared toward lighter industrial and warehouse applications. XCMG provides mobile gantry cranes and heavy-duty lifting equipment with custom solutions for demanding industrial and construction requirements. Demag Cranes & Components offers precision-engineered modular gantry designs, including mobile variants for industrial material handling. Henan FineWork Cranes Co., Ltd. manufactures portable gantry cranes with custom solutions, including adjustable spans and heights for varied heavy-load environments.
Worldwide Portable Gantry Crane Market
What unites these competitors is not a single technology but a shared need to translate mechanical reliability into application outcomes. In a fragmented market, advantage increasingly comes from configurable product families, integration with site workflows, and the ability to support customers through installation, training, and maintenance. Companies that can demonstrate measurable reductions in setup time, safer load handling, and lower lifecycle friction are better positioned to defend pricing and win recurring service relationships.
Forces Reshaping Demand and Cost Structures
Beyond segmentation and competition, several external forces are rewriting the rulebook for portable gantry crane procurement and product planning. Automation and Industry 4.0 practices are accelerating the adoption of lifting equipment with enhanced precision, control, and safety features. As material handling operations seek repeatable throughput and reduced manual variability, demand is tilting toward cranes that can interface cleanly with broader site systems and support consistent lift performance. This is not an automation trend limited to large fixed installations; portable and mobile gantry cranes are increasingly expected to deliver smarter control, clearer load visibility, and safer operation in dynamic environments.
At the same time, input cost and trade policy dynamics are reshaping the economics of supply. The increase in US Section 232 steel tariffs from 25 percent to 50 percent effective June 2025 has altered raw material costs for domestic crane manufacturers, adding pressure to cost structures that rely on steel-intensive fabrication. For procurement leaders, this underscores the importance of sourcing scenarios, lead-time resilience, and specification flexibility. For manufacturers, it raises the stakes around material mix, regional production strategy, and value-based pricing. Steel price stability in the United States through 2025, alongside moderate upward movement in Chinese benchmark pricing in 2026, suggests that cost volatility will remain a monitoring priority even as the broader trend stays contained.
These forces combine to create a market where the winning strategy is rarely about price alone. It is about aligning crane specifications with operational realities, anticipating regulatory and input-cost shifts, and selecting partners who can support the full lifecycle of the equipment. In that context, short-term procurement decisions carry long-term consequences for uptime, safety, and total cost of ownership.
What the Full Study Delivers for 2026 Decision-Making
The complete PW Consulting study translates these macro signals into an operational intelligence package built for executive, product, and commercial teams. It provides a validated historical baseline and a forward forecast that can anchor budget planning, capacity decisions, and market-entry evaluations. It dissects the segmentation structure in a way that helps organizations identify which material, capacity, end-user, and regional profiles are most relevant to their position, without forcing a one-size-fits-all interpretation. It maps the competitive field with company-level profiling, recent activity, and development signals that reveal where capabilities are being reinforced and where differentiation is likely to intensify.
Equally important, the study integrates the environment in which these companies and customers operate. Raw material trends, trade policy developments, and automation-driven demand shifts are woven into the analysis so that readers can connect market numbers to actionable levers. The result is a framework for evaluating not just where the market is going, but how to respond in a way that protects margins, improves specification accuracy, and reduces exposure to cost or compliance surprises.
For organizations making 2026 decisions—whether selecting lifting equipment for a new facility, refining a product roadmap, assessing supplier portfolios, or prioritizing regional expansion—the study offers the granularity required to move from directional confidence to precise planning. It is structured to support scenario comparison, vendor evaluation, and demand forecasting with a level of detail that general market summaries cannot provide.
Why This Intelligence Matters Now
The portable gantry crane market is expanding at a steady, structural pace, but the value at stake is determined by how well organizations interpret segmentation, cost drivers, and competitive dynamics. A mid-single-digit growth trajectory can still produce markedly different outcomes depending on where a company plays and how it configures its offering or procurement strategy. In a fragmented landscape with evolving material costs and rising expectations for precision and safety, the organizations that outperform will be those that treat market intelligence as a decision tool rather than a benchmark.
This preview has outlined the scale of the opportunity, the segmentation forces that matter, the competitive logic now in play, and the external variables that will influence costs and demand. The full report goes further, delivering the detailed segmentation read, company-level context, and forward-looking scenario structure needed to convert insight into action. For leaders who need to align capital, product, and procurement decisions with where the market is actually heading, the complete study provides the intelligence foundation to do so with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Gantry Crane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aviation Fuel Storage Tank Market to Hit $2,593.54M by 2032 at 5.19% CAGR
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Worldwide Aviation Fuel Storage Tank Market: A 2026 Outlook
The global aviation industry stands at a critical juncture where infrastructure resilience meets the urgent demand for sustainable operations. As air travel recovers and evolves, the backbone of refueling operations—the storage tank infrastructure—requires unprecedented attention. For stakeholders navigating the complex landscape of fuel storage, understanding the macroeconomic trajectory and structural shifts within the market is no longer optional; it is a strategic necessity. Our latest comprehensive analysis of the Worldwide Aviation Fuel Storage Tank Market offers a detailed roadmap for navigating the period from 2026 through 2032, providing the intelligence needed to secure operational continuity and capitalize on emerging growth vectors.
This market research is designed to equip decision-makers with a granular understanding of value chains, competitive pressures, and regulatory headwinds. By synthesizing historical performance data with forward-looking projections, we illuminate the pathways that will define market leadership in the coming decade. The following insights summarize the strategic value embedded within this report, highlighting why immediate engagement with these findings is crucial for capital allocation and risk management.
Market Trajectory and Growth Dynamics
The economic fundamentals of the aviation fuel storage sector demonstrate robust resilience and steady expansion. Based on historical analysis spanning from 2020 to 2025, the market has exhibited consistent upward momentum, transitioning from a revenue valuation of approximately 1,415 million USD to over 1,820 million USD in the base year. This growth trajectory sets a strong foundation for the forecast period covering 2026 to 2032.
Historical Performance and Future Projections
The data indicates a mature yet accelerating market environment. Starting from 2020, the market has navigated through various global disruptions to establish a stable growth pattern. By 2025, the market size reached 1,820 million USD, reflecting a compounded increase over the preceding five years. Looking ahead, the forecast period projects a steady climb, with the market expected to breach the 2 billion USD threshold by 2027 and continue ascending toward 2,593.54 million USD by 2032.
The compound annual growth rate (CAGR) for the forecast period is estimated at 5.19 percent. This rate underscores a healthy demand environment driven by infrastructure upgrades, safety compliance mandates, and the expansion of airport capacities globally. For investors and industry participants, this growth rate signals a stable return profile, provided that entry strategies are aligned with the specific segments driving this expansion. The transition from 2026 to 2032 represents a period where capital expenditure on storage infrastructure will likely outpace general inflation, driven by the need for modernization and regulatory adherence.
Structural Segmentation and Value Distribution
Understanding where value resides within the market is essential for targeted investment. Our report dissects the market into critical operational dimensions, revealing how different segments contribute to the overall revenue pool. While specific percentage breakdowns are reserved for the full dataset, the absolute revenue contributions highlight the dominant areas of activity.
Worldwide Aviation Fuel Storage Tank Market
Regional Revenue Contributions
Geographically, the market is distributed across key industrial hubs. Asia Pacific represents a significant portion of the revenue landscape, contributing over 630 million USD, reflecting the region's aggressive airport expansion and increasing air traffic density. North America follows closely with contributions exceeding 511 million USD, driven by stringent safety regulations and ongoing mid-life infrastructure upgrades at legacy hubs. Europe accounts for over 424 million USD, while the Middle East & Africa and Latin America contribute 163.47 million USD and 90.37 million USD respectively. These figures illustrate the global nature of the demand, though concentration varies significantly based on aviation penetration and fuel logistics requirements.
Tank Type and Installation Preferences
The choice of storage technology remains a pivotal decision for airport planners. The market sees substantial activity in Fixed Roof Tanks, generating approximately 982.48 million USD, which indicates a strong preference for cost-effective storage solutions for stable fuel inventories. Floating Roof Tanks contribute around 837.52 million USD, often selected for specific environmental compliance needs or volatile inventory management.
Installation methodology further delineates the market structure. Above-Ground Storage Tanks (AST) dominate the landscape with a valuation near 1,344.06 million USD, favored for ease of inspection and compliance with modern safety standards. Underground Storage Tanks (UST) account for 475.94 million USD, typically utilized in specific spatial constraints or environmental protection scenarios. The balance between AST and UST often depends on local zoning laws and the specific risk profile of the storage location.
End-User Segmentation
Commercial Airports remain the primary revenue driver, engaging storage solutions valued at approximately 1,294.39 million USD. This dominance is expected given the volume requirements of commercial jet operations. Military Airbases follow with a contribution of 434.74 million USD, where strategic reserve capabilities and ruggedized storage solutions are prioritized. General Aviation, while smaller in scale at 90.87 million USD, represents a niche but high-growth segment, particularly with the rise of private aviation and regional connectivity initiatives.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a moderate level of concentration, where scale and specialization allow key players to secure significant market share. The top three companies hold a combined market share of 28.5 percent, while the top five extend this to 42.3 percent. This indicates a competitive environment where the top tier commands substantial influence, yet a long tail of specialized manufacturers competes on customization, speed, and regional compliance.
Key Industry Participants
Several established players define the competitive baseline, each bringing distinct capabilities to the market:
- Ace Tank and Fueling Equipment: Based in the United States, this firm specializes in customized, fully-equipped aboveground storage tanks tailored specifically for airport fuel distribution networks, emphasizing turnkey integration.
- Tate Metalworks: Also US-based, Tate focuses on field-erected solutions using stainless steel, duplex steel, and carbon steel. Their engineering focus is increasingly directed toward sustainable aviation fuel (SAF) compatibility alongside conventional fuel requirements.
- AGI Westeel: Operating out of Canada, AGI Westeel provides shop-fabricated aboveground steel aviation tanks designed to meet rigorous Canadian Aviation Regulations, ensuring safe storage protocols are met from the outset.
- Center Enamel: A China-based specialist, Shijiazhuang Zhengzhong Technology Co., Ltd., focuses on corrosion-resistant stainless steel tanks with aluminum dome roofs. Their systems are optimized for Jet A-1 fuel purity and high-volume applications, recently emphasizing ultra-cleanliness and modular containment.
- Unity Fuel Solutions: This US manufacturer emphasizes quality and cleanliness, producing double-walled aboveground storage tanks for Jet A-1 and Avgas, catering to airports with strict fuel handling standards.
- Fuelchief: From New Zealand, Fuelchief supplies the SuperVault Aviation range, offering 4-hour fire-rated flammable storage tanks suitable for everything from helipads to full jet operations, addressing critical safety ratings.
- Avioneco: Based in Poland, this company produces double-walled steel tanks in both mobile and stationary configurations. Their solutions cover AVGAS, JET-A1, and MOGAS, providing flexibility for airfields with varying refueling needs.
- SEI Industries: A Canadian manufacturer known for the Bulk Aviation Transport Tank (BATT), a collapsible tank approved for air transport of aviation fuel (Class 3 UN 1863), addressing logistics flexibility.
- Western Global: Located in the United States, they manufacture transportable and static fuel storage tanks, including models certified for aviation fueling applications, bridging the gap between mobility and fixed infrastructure.
- Varec: Also US-based, Varec provides end-to-end fuel management solutions, including tank farm automation and level measurement for storage tanks at major airports, adding a technology layer to physical storage.
- eN-TANK Sp. z o.o. sp.k.: A Polish entity specializing in steel double-wall tanks for petroleum products including aviation fuels since 2002, leveraging long-term experience in double-wall integrity.
- CZ Ltd: A UK supplier with over 60 years of experience, providing aviation fuel storage tanks and systems for Jet A1 and Avgas, representing a legacy of design and manufacture expertise.
Recent Industry Developments and Project Intelligence
Real-time intelligence on project commissioning and planning provides early signals of demand shifts. Our research team tracks these milestones to validate market momentum.
Aircraft Fuel Tanks Market
- Jefferson County Airport (February 2026): The completion of a 12,000-gallon unleaded aviation fuel bulk storage tank installation was reported as part of the AIP-70 Unleaded Fuel Tank Project. This initiative supports wholesale deliveries of Swift Fuels UL94, signaling a tangible shift toward unleaded alternatives in general aviation infrastructure.
- Center Enamel (November 2025): The release of advanced stainless steel Jet A-1 fuel storage tank systems emphasized ultra-cleanliness and zero-tolerance quality control. This product certification highlights the industry's move toward modular containment optimized for global aviation logistics and stricter purity standards.
- Sonoma County Airport (October 2025): The Board approved an engineering and budget study for a new aircraft fuel storage facility. The objective is to more than double existing storage capacity, indicating significant public investment in regional airport infrastructure to accommodate future traffic growth.
Regulatory and Material Market Context
Strategic planning cannot occur in a vacuum; it must account for the raw material environment and the regulatory framework governing storage safety and sustainability.
Raw Material Cost Dynamics
The cost of steel, a primary input for tank manufacturing, influences project budgets and margins. As of mid-2025, U.S. Midwest hot-rolled coil steel prices stabilized in the low to mid $800s per short ton, with futures indicating range-bound trading into early 2026. This stability offers a predictable input cost environment for North American projects. Meanwhile, Chinese steel rebar benchmark prices stood at 3,103 CNY per tonne as of April 2026. These divergent regional price points influence the competitive positioning of manufacturers sourcing materials globally, affecting the landed cost of imported tank systems versus locally fabricated ones.
Regulatory Standards and Compliance
Safety and environmental performance are governed by evolving standards. The publication of API Standard 650, 13th Edition for Welded Tanks for Oil Storage, enhances safety and sustainability requirements applicable to aviation fuel applications. Compliance with this standard is becoming a baseline expectation for new installations and major retrofits.
In the United States, federal policy is also shaping the economic viability of fuel storage associated with emerging fuel types. The Section 45Z Clean Fuel Production Credit provides applicable amounts ranging from $0.20 to $1.00 per gallon for non-SAF transportation fuels produced after December 31, 2025, with specific rules for domestically sourced feedstocks from the US, Mexico, or Canada. While this credit targets production, it indirectly incentivizes the storage and distribution infrastructure required to handle these fuels, stimulating demand for compliant storage solutions that can handle varied fuel chemistries.
Furthermore, physical safety standards remain paramount. Storage tanks for aviation fuel must comply with UL 142 for steel aboveground tanks for flammable and combustible liquids or UL 2085 for protected tanks. These standards are referenced in FAA and DOI aviation fuel management guidelines, making certification a prerequisite for operational legality in many jurisdictions. Ignoring these compliance pathways exposes operators to significant liability and operational risk.
Strategic Recommendations for 2026 and Beyond
For executives and investors, the data suggests several actionable strategic postures. First, the growth trajectory supports continued investment in storage capacity, particularly in regions showing high absolute revenue contribution like Asia Pacific and North America. However, success depends on navigating the complexity of tank types and installation methods. The dominance of Above-Ground Storage Tanks suggests that procurement strategies should prioritize AST suppliers with strong safety certifications and modular capabilities.
Second, the competitive landscape indicates that partnerships with specialized manufacturers who offer end-to-end management, such as tank farm automation, may provide a competitive edge. As seen with providers like Varec, integrating technology with physical storage enhances operational efficiency and reduces leakage risks. Third, the regulatory environment regarding unleaded fuels and SAF compatibility requires forward-looking procurement. Projects like the Jefferson County Airport installation demonstrate that early adoption of infrastructure capable of handling unleaded blends positions operators ahead of regulatory curves and fuel supply shifts.
Finally, supply chain resilience is critical given the variations in global steel pricing. Locking in supply agreements or utilizing local fabrication partners in stable price regions can mitigate margin erosion. The market is not merely about buying tanks; it is about securing a compliant, safe, and efficient fuel supply chain that can withstand the operational demands of the next decade.
Conclusion
The Worldwide Aviation Fuel Storage Tank Market offers a landscape of steady growth and evolving technical requirements. With a projected market size approaching 2.6 billion USD by 2032 and a CAGR of 5.19 percent, the opportunity for strategic positioning is substantial. However, realizing this value requires deep insight into the segmentation dynamics, competitive capabilities, and regulatory constraints that define the sector.
This article provides a high-level overview of the market intelligence available. To access the full granularity of data—including exact segment percentages, detailed regional growth matrices, comprehensive company profiling, and risk analysis frameworks—we invite you to explore the complete Worldwide Aviation Fuel Storage Tank Market research report. Equip your organization with the definitive intelligence needed to navigate the complexities of aviation fuel infrastructure in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Aviation Fuel Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Medical Network Isolators Market to Hit $300.81M by 2032, 6.45% CAGR
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Connected Healthcare Era: Inside the Worldwide Medical Network Isolators Market
The modern hospital is no longer a collection of standalone devices but a densely interconnected ecosystem where patient data, imaging streams, and life-support systems communicate across Ethernet backbones in real time. As this connectivity deepens, so does the imperative to guarantee galvanic separation, limit leakage currents, and protect vulnerable medical equipment from potential differences that travel along data cables. Our latest worldwide market study on medical network isolators maps this evolving landscape with the precision that procurement leaders, R&D directors, and regulatory affairs teams require to make confident investment decisions throughout 2026 and beyond.
The research anchors its perspective in a five-year historical window spanning 2020 through 2025, then projects forward across a seven-year forecast horizon from 2026 to 2032. This structure allows decision-makers to ground strategic plans in observed trajectory rather than speculative optimism. The overall market size has expanded from approximately 145.2 million USD in 2020 to 194.2 million USD in the 2025 base year, reflecting sustained demand driven by hospital modernization programs, tighter patient-safety expectations, and the proliferation of networked diagnostic and therapeutic equipment. The forecast period continues this upward path, reaching an estimated 214.24 million USD in 2026 and climbing toward 300.81 million USD by 2032. Over the full forecast window, the compound annual growth rate settles at 6.45 percent, a figure that signals steady, structurally supported expansion rather than a temporary cycle.
Worldwide Medical Network Isolators Market
For executives evaluating capital allocation, product roadmaps, or regional entry strategies, these macro indicators serve as a calibration point. Growth is not uniform across every segment, geography, or product architecture, and that unevenness is precisely where strategic advantage is created. The study deliberately avoids flattening the market into a single narrative. Instead, it dissects the demand structure so that leadership teams can identify which subsegments warrant deeper investment, which supply constraints demand contingency planning, and where regulatory momentum is reshaping procurement requirements.
Digital Isolators Market
Volume and Share Distribution Across Segments
Understanding where revenue concentrates is essential for prioritizing commercial efforts and engineering resources. The report breaks down the market across three dimensions that matter most to buyers and suppliers: geography, product type, and clinical application. In 2025, regional revenue distribution shows a clear hierarchy that mirrors the maturity of healthcare infrastructure and the pace of networked device adoption. North America accounts for 73.64 million USD of total revenue, reflecting dense hospital networks, robust capital equipment cycles, and early adoption of networked imaging and navigation systems. Europe follows with 53.53 million USD, supported by established medical device regulations and continued retrofitting of legacy facilities. Asia Pacific contributes 48.52 million USD, a segment shaped by rapidly expanding diagnostic capacity, growing private hospital chains, and increasing import and localization activity. Latin America records 9.99 million USD, while the Middle East and Africa account for 8.52 million USD, both regions representing high-potential but structurally different demand environments that require distinct go-to-market approaches.
The type segmentation reveals how engineering preferences differ across installation contexts. External network isolators represent the largest value pool at 131.8 million USD, reflecting their role as field-installable protection modules for existing Ethernet infrastructure in patient care vicinities. Wall-mounted network isolators contribute 41.04 million USD, capturing demand from fixed installation scenarios where space, compliance, and serviceability are paramount. Built-in OEM modules account for 21.36 million USD, a smaller but strategically significant pool tied to equipment manufacturers integrating isolation at the design stage rather than relying on post-market add-ons. These distinctions matter because each type carries different certification burdens, integration timelines, and procurement cycles.
Application segmentation further clarifies where demand originates on the clinical floor. Hospitals and clinics generate 111.23 million USD, the dominant environment for network isolation given the breadth of connected devices and the strictness of safety requirements in patient-adjacent areas. Diagnostic imaging centers contribute 51.56 million USD, reflecting the high data-throughput needs of imaging networks and the sensitivity of diagnostic equipment to electrical disturbances. Surgical suites account for 31.41 million USD, a specialized segment where isolation is often evaluated not only for safety but also for operational continuity during critical procedures. Together, these segments illustrate a market in which isolation is no longer an accessory but a design requirement tied to device certification, facility compliance, and risk management.
Competitive Dynamics and Supplier Positioning
The market is not fragmented in the traditional sense, but neither is it dominated by a single supplier architecture. The report places the competitive landscape in context by examining the players who shape product standards, certification practices, and purchasing expectations. Baaske Medical GmbH stands out for its TÜV-certified medical network isolators, including the MI 1005 series and the MI 2005 designed for 2.5 GBit/s throughput. Its product line is engineered to comply with IEC 60601-1 Edition 3.2, emphasizing galvanic isolation in patient care vicinities and protection against leakage currents, overvoltages, and electrostatic discharge for Ethernet connections in hospitals and medical devices. For procurement teams, this level of certification specificity matters because it reduces integration risk and shortens compliance verification cycles.
EMO Systems GmbH, operating under the EMOSAFE brand, provides network isolators such as the EN-1005+ and EN-70 series for medical applications. Its offerings are designed to conform to IEC 60601-1 with high dielectric strength, reaching up to 5 kV AC and 8.5 kV DC, alongside UL recognition and support for Gigabit-plus Ethernet. The emphasis on galvanic separation and patient safety in medical electrical devices positions EMOSAFE as a supplier aligned with environments where electrical robustness and regulatory recognition are equally important. Eaton, through its Tripp Lite series, contributes hospital-grade medical Ethernet network isolators such as the N234-MI-1005, a Cat6 RJ45 solution compliant with IEC 60601-1 and UL 60601-1. Its value proposition centers on isolating medical equipment from leakage currents on Ethernet networks in patient care vicinities, a concern that remains highly relevant as hospitals connect devices to non-medical infrastructure. Phoenix Contact rounds out the competitive field with passive network isolators such as the FL ISOLATOR 100-RJ/SC, providing up to 4 kV protection against potential differences. Its approach is particularly relevant for integration scenarios in medical and industrial settings where galvanic isolation must be achieved without adding external power dependencies.
The study also situates these supplier profiles within broader competitive metrics. Market concentration data shows a CR3 of 38.5 percent and a CR5 of 52.3 percent, indicating that while leading players hold meaningful share, the market still leaves substantial room for specialized suppliers, regional distributors, and OEM-embedded solutions. This structure has practical implications for sourcing strategy. Buyers can leverage multi-supplier validation to manage supply continuity, while suppliers must differentiate on certification breadth, throughput capability, installation form factor, and post-sales technical support rather than price alone.
Regulatory Pressure as a Market Accelerator
One of the most consequential themes in the research is the way regulatory requirements are converting network isolation from a desirable feature into a procurement mandate. Medical network isolators for Ethernet connections in patient care vicinities must comply with IEC 60601-1:2005/AMD1:2012/AMD2:2020, Edition 3.2, which defines reinforced insulation at the 2 MOPP level and requires galvanic separation to limit leakage currents. This is not a marginal specification; it shapes product architecture, validation documentation, and the way hospitals evaluate components during facility upgrades or equipment refreshes. Suppliers that align their offerings with these requirements gain a compliance shortcut, while buyers gain a clearer basis for specification writing and audit readiness.
The regulatory environment also interacts with certification ecosystems beyond the IEC baseline. EMOSAFE network isolators conform to IEC 60601-1 requirements for SIP and SOP interfaces on medical electrical equipment, with additional UL recognition as components for safe operation in medical environments. Eaton Tripp Lite medical Ethernet isolators such as the N234-MI-1005 comply with IEC 60601-1 and IEC 60601-1-2 EMC standards specifically for network connections between medical devices and non-medical Ethernet infrastructure in patient vicinities. These overlapping standards create a compliance matrix that procurement teams must navigate carefully, and the report maps that matrix so that readers can see where certification convergence reduces friction and where gaps still require custom validation.
Passive medical network isolators add another dimension to the regulatory discussion. By providing galvanic isolation without external power, they interrupt all conductive connections, including conductors and shielding, preventing the equalization of potential differences via data cables in healthcare settings. This passive approach appeals in scenarios where adding power-dependent components would complicate installation or introduce new failure modes. At the same time, it places greater importance on component quality, dielectric performance, and long-term reliability documentation, all of which are addressed in the study through supplier-level technical analysis.
Operational Reliability and the Cost of Downtime
Market growth is not only a function of regulation and device proliferation; it is also tied to the operational consequences of communication failure. Networked medical systems depend on stable Ethernet links for data integrity, device coordination, and clinical workflow continuity. When communication anomalies appear, isolation components can become part of troubleshooting workflows. A recent example from April 2025 illustrates this dynamic: during a malfunction analysis involving Medtronic Navigation, Inc., a network isolator component was replaced while troubleshooting a communication failure in a navigation system. Post-analysis showed no fault confirmed in the returned isolator. While the outcome did not attribute the failure to the isolator itself, the event highlights how isolation components are now embedded in the operational accountability chain for connected medical equipment.
For healthcare providers and device manufacturers, this has strategic implications. It reinforces the need to specify isolation components that are not only compliant but also traceable, serviceable, and supported by clear failure-mode documentation. It also underscores the value of supplier partnerships that extend beyond initial purchase, including technical support, replacement logistics, and compatibility assurance across network architectures. The report examines these operational realities in depth, showing how reliability expectations are reshaping both product design and procurement criteria.
What the Study Delivers Beyond the Top-Line Numbers
The headline market size and growth rate provide orientation, but the real strategic value of the study lies in its operational detail. The report moves beyond summary statistics to deliver content that can be used immediately in planning sessions, specification reviews, and investment committees. It covers the historical trajectory from 2020 through 2025, then projects the market across the 2026 to 2032 forecast period with a structured methodology that connects demand drivers to segment outcomes. It evaluates how type, application, and regional dynamics interact rather than treating them as isolated lenses, which is essential because real-world purchasing decisions rarely follow a single segmentation line.
The study also includes competitive profiling that goes past corporate descriptions. It examines how leading suppliers position themselves against regulatory requirements, throughput expectations, installation preferences, and certification ecosystems. This allows readers to compare not only what companies offer but why they matter in specific procurement contexts. In addition, the research integrates regulatory developments, technical conformity details, and operational case context so that decision-makers can see how compliance, performance, and reliability intersect in day-to-day purchasing and engineering choices.
For teams planning 2026 initiatives, this level of detail supports several practical outcomes. It helps identify where specification requirements are tightening and where procurement cycles may lengthen or shorten. It highlights which product architectures are gaining traction in specific installation environments, and where built-in OEM integration may shift demand away from field-installable add-ons. It also provides a framework for evaluating supplier resilience, including certification coverage, throughput range, and the ability to support both passive and powered isolation strategies where needed.
How to Use This Intelligence in 2026 Planning
The worldwide medical network isolators market is entering a phase in which growth is supported by structural factors rather than short-term cycles. Hospital connectivity continues to expand, regulatory expectations for patient-adjacent Ethernet infrastructure remain stringent, and device manufacturers are increasingly designing isolation into products rather than treating it as an afterthought. In that environment, the organizations that make the best decisions will be those that can connect top-line market direction to segment-level reality, supplier capability, and compliance requirements.
This study is built to support that decision-making. It gives leadership teams a defensible view of where the market has been, where it is headed, and which variables will matter most as 2026 plans are finalized. It also preserves the deeper numerical and supplier-level intelligence that procurement, engineering, and strategy teams need to act with precision. To access the full segmentation analysis, regional breakdowns, type and application detail, and complete competitive and regulatory mapping, readers are invited to explore the full research on the source page. The complete report transforms these high-level insights into actionable intelligence, allowing organizations to move from market awareness to informed execution.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Network Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Remicade Market to Reach USD 4,950M in 2025, Shrinking at -4.52% CAGR Through 2032
By pmarketresearch, 2026-09-17
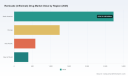
Navigating the Decline: Strategic Imperatives in the Global Remicade (Infliximab) Drug Market Through 2032
The global therapeutic landscape for monoclonal antibodies has long been defined by blockbuster agents that reshaped standard care across multiple autoimmune indications. Among these, Remicade (infliximab) stands as a foundational reference product, yet its commercial trajectory has entered a period of structural contraction. As biosimilar penetration deepens and originator revenue streams compress, pharmaceutical executives, market access leaders, and investment strategists require a granular, forward-looking analysis to navigate the coming years with confidence. Our newly released Worldwide Remicade (infliximab) Drug Market research delivers precisely that intelligence, synthesizing historical performance, competitive positioning, and multi-year forecasts into a decision-ready framework.
This executive overview outlines why this study is an essential strategic asset for 2026 planning cycles. It highlights the macroeconomic contours of the market, maps the evolving competitive architecture, details the operational contents of the full report, and demonstrates how procurement, pricing, and pipeline teams can translate these insights into measurable advantage. Crucially, the complete dataset—covering regional revenue trajectories, indication-level demand shifts, product-type dynamics, and company-specific market share estimates—resides within the full publication, accessible through our research portal.
The Macro Trajectory: A Contraction Shaped by Biosimilar Maturity and Payer Pressure
Understanding where the Remicade market is heading begins with acknowledging its historical arc. Over the 2020–2025 period, global revenue for infliximab products has followed a consistent downward slope, reflecting the irreversible shift from a single originator-dominated ecosystem to a fragmented, price-competitive biosimilar marketplace. Our model places the 2025 baseline at approximately $4,950 million, down from roughly $8,240 million at the start of the historical window. This compression is not a transient cycle but a structural realignment driven by patent expirations, tender-based procurement, and deliberate payer policies that reward lower-cost alternatives without compromising clinical outcomes.
Looking forward, the forecast period spanning 2026 through 2032 projects a continued contraction, with the compound annual growth rate indicating a decline of roughly 4.52 percent across the analysis horizon. By 2032, total market value is projected to settle near the $3.58 billion mark. Executives should interpret this trajectory not as market failure but as market maturation. The value pool is being redistributed: originators retain premium positioning in specific channels and patient segments, while biosimilar manufacturers capture volume through aggressive pricing, formulary placements, and emerging-market access programs.
Several structural forces reinforce this path. Cold-chain logistics and biologic manufacturing complexity continue to dominate cost-of-goods profiles, constraining the pace at which new entrants can scale without sacrificing quality or margin. Simultaneously, reimbursement architectures across major healthcare systems increasingly treat infliximab biosimilars as interchangeable options within treatment algorithms, accelerating utilization in rheumatoid arthritis, Crohn’s disease, ulcerative colitis, psoriatic arthritis and psoriasis, and ankylosing spondylitis. The strategic question for 2026 is no longer whether biosimilar share will grow, but how companies will defend or capture value as the remaining originator revenue erodes and biosimilar price competition intensifies.
Worldwide Remicade (infliximab) Drug Market
Competitive Architecture: Coexistence, Substitution, and Strategic Differentiation
The competitive landscape for infliximab is unusually dense, spanning the originator firm, a cohort of established biosimilar developers, and a second wave of emerging-market suppliers targeting price-sensitive channels. This fragmentation creates a multilayered battlefield where commercial strategy must be tailored to geography, formulation, distribution model, and payer relationship rather than applied uniformly.
Janssen Biotech, Inc. (Johnson & Johnson) remains the anchor of the reference-product ecosystem. As the originator of intravenous Remicade, the company continues active global commercialization, including promotion of an unbranded infliximab variant in select contexts. Its Q1 2026 worldwide sales reporting of $422 million illustrates both the resilience of the brand in remaining formulary positions and the steady headwind from biosimilar substitution and patient-mix shifts. For strategists, Janssen’s trajectory signals that originator value is increasingly tied to channel control, patient support programs, and relationship-driven procurement rather than volume dominance.
On the biosimilar side, Celltrion, Inc. has emerged as a formulation innovator. The company markets Remsima (CT-P13) IV biosimilar and Zymfentra (infliximab-dyyb) subcutaneous formulation, while also offering the world’s first liquid IV infliximab formulation. A recent European Commission marketing authorization for the Remsima IV liquid across all prior indications—including rheumatoid arthritis, Crohn’s disease, and ulcerative colitis—represents a meaningful operational advantage by reducing preparation complexity and potentially improving infusion-center efficiency. This kind of formulation-level differentiation is exactly the type of lever that can shift purchasing decisions in hospital and institutional settings.
Worldwide Belimumab Market
Pfizer Inc. continues to compete through Inflectra (infliximab-dyyb) and Ixifi (infliximab-qbtx) across multiple markets, leveraging broad commercial infrastructure. Samsung Bioepis Co., Ltd., in partnership with Organon & Co., commercializes Renflexis (infliximab-abda) in the United States and Flixabi (SB2) in Europe, demonstrating how co-commercialization and licensee relationships can extend reach without duplicating fixed costs. Amgen Inc. markets Avsola (infliximab-axxq), while Sandoz Group AG (a Novartis division) offers Zessly (infliximab) biosimilar in Europe and other regions. Viatris Inc. remains active through its legacy Mylan portfolio and select partnerships, and a broader tier of suppliers—including Biocon Biologics, Dr. Reddy’s Laboratories, Teva Pharmaceutical Industries, Fresenius Kabi AG, STADA Arzneimittel AG, Intas Pharmaceuticals, and Zydus Lifesciences—operates with a deliberate focus on emerging markets, tender-based supply, and cost-sensitive regions.
This architecture matters because pricing, access, and supply reliability are no longer determined by a single reference price. Instead, procurement teams evaluate a matrix of product specifications, cold-chain readiness, batch consistency, regulatory status by territory, and contractual flexibility. The full report dissects these dynamics company by company, enabling buyers and competitors to benchmark positioning with precision.
Structural Drivers: Regulation, Reimbursement, and Manufacturing Realities
Three interlocking dynamics define the operating environment for infliximab products and shape every strategic choice made in 2026.
First, regulatory milestones have already unlocked the biosimilar market. Remicade patents expired in the European Union in February 2015 and in the United States in September 2018, enabling multiple biosimilar entries. The FDA has since approved a sequence of infliximab biosimilars, including Inflectra (2016), Renflexis (2017), Ixifi (2017), and Avsola (2019), with continued utilization across autoimmune indications. These approvals are not historical footnotes; they are the foundation of today’s market structure and the reason why formulary decisions, interchangeability designations, and national procurement frameworks now operate under a biosimilar-friendly paradigm.
Second, reimbursement and pricing behavior are actively redistributing the value pool. Infliximab biosimilars have demonstrated average price discounts ranging from roughly 19 to 59 percent versus pre-biosimilar Remicade list prices, generating measurable cost savings for payers and healthcare systems. In the US, biosimilar market share reached approximately 48 percent by Q3 2024 and continued incremental gains into 2025, driven by payer preferences and lower average selling prices. Early 2025 data suggest biosimilars captured an estimated 48 to 53 percent share in the US, with gradual further uptake expected as tenders renew and formulary placements consolidate. For commercial teams, the implication is clear: list-price competition is being replaced by negotiated, volume-linked, and channel-specific pricing models, and success depends on contractual design as much as product quality.
Third, manufacturing and supply-chain economics remain a binding constraint. Biologic manufacturing complexity, including cold-chain logistics for monoclonal antibodies, continues to be a primary cost driver alongside active pharmaceutical ingredient production. This reality influences everything from tender competitiveness to risk of supply disruption and from geographic expansion sequencing to margin sustainability. Companies that can demonstrate reliable cold-chain capacity, consistent batch release, and defensible cost structures will command disproportionate leverage in institutional and government procurement contexts.
Inside the Report: Operational Content Designed for 2026 Decision-Making
Our Worldwide Remicade (infliximab) Drug Market study is structured to convert market complexity into actionable plans. Rather than offering high-level commentary, the report delivers operational content that procurement, pricing, market access, and business development teams can apply directly during planning cycles. The full publication includes:
- A comprehensive historical analysis covering the 2020–2025 window, establishing the baseline for trend interpretation and benchmarking current performance against prior-year dynamics.
- A forecast model extending through 2032 that quantifies the expected revenue trajectory at the total market level and isolates the drivers behind the projected decline, including biosimilar share gains, pricing compression, and indication-level demand evolution.
- Detailed segmentation analysis by region, product type, and indication, enabling readers to understand where value is concentrating, where substitution is accelerating, and which therapeutic areas retain the strongest pricing resilience.
- A competitive benchmarking module that evaluates the positioning, formulation strategies, geographic footprints, and commercial models of the key players shaping the infliximab ecosystem.
- Thematic analysis of regulatory timelines, reimbursement behavior, price discount ranges, and manufacturing and cold-chain constraints, integrated into a cohesive view of market dynamics rather than treated as isolated facts.
- Identification of recent developments and their strategic implications, including formulation-level approvals and quarterly sales signals that indicate how the competitive balance is shifting in real time.
Each section is designed to support a specific decision type. Procurement leaders can use the segmentation and pricing themes to structure tender evaluations and negotiate volume commitments. Pricing and market access teams can leverage the discount-range analysis and payer-behavior insights to model formulary positioning and contract architectures. Business development and competitive intelligence teams can use the company-level profiling and strategic context to assess partnership opportunities, geographic entry sequencing, and formulation-driven differentiation. The complete version of the report presents the underlying figures, regional and indication-level breakdowns, and company-specific estimates in full, ensuring that readers can validate assumptions and build internal models with confidence.
Strategic Implications for 2026 Planning Cycles
For executives entering 2026, the Remicade market demands a shift from volume-defensive thinking to value-positioning discipline. Several implications stand out.
Originator and reference-product teams must prioritize channel control, patient support, and relationship-based procurement to sustain relevance as biosimilar volume grows. The focus should be on protecting high-value segments, optimizing unbranded or supportive offerings, and aligning sales resources with the channels where clinical integration and service quality still differentiate the reference product.
Biosimilar developers should differentiate through formulation convenience, supply reliability, and contractual flexibility rather than price alone. The recent European authorization of a liquid IV infliximab formulation highlights how reduced preparation burden can resonate with infusion centers and hospital pharmacy operations. Where price competition is intense, margin defense depends on manufacturing efficiency, cold-chain capability, and the ability to secure recurring volume through tenders and institutional contracts.
Payers, procurement organizations, and healthcare systems should treat infliximab as a case study in managed substitution. With biosimilar discounts materially below pre-biosimilar list prices and utilization expanding across core autoimmune indications, the opportunity lies in structuring contracts that lock in savings while preserving supply continuity and clinical equivalence. Forecasting models that fail to account for incremental biosimilar uptake, indication-level demand patterns, and regional procurement cycles will overestimate remaining originator revenue and underestimate total cost savings.
Investors and market analysts should frame the market as a redistribution story rather than a collapse. Revenue is migrating from a single originator to a diverse set of biosimilar suppliers, with regional variation in pace and depth. Concentration among top players remains significant, underscoring the importance of understanding which firms control which channels and how partnership arrangements shape commercial reach. The full report quantifies these concentration dynamics and regional splits so that stakeholders can map risk and opportunity with precision.
Conclusion: Accessing the Full Intelligence
The Worldwide Remicade (infliximab) Drug Market is undergoing a measured but unmistakable contraction, shaped by mature biosimilar competition, aggressive payer cost management, and the enduring complexity of biologic manufacturing and distribution. For organizations operating in this space, the strategic imperative in 2026 is to replace assumptions with evidence: to know where value is eroding, where it is being captured, and which operational levers will determine outcomes over the 2026–2032 horizon.
This executive preview has outlined the macro trajectory, the competitive architecture, the structural drivers, and the operational content embedded in our research. The complete market size figures, regional and indication-level breakdowns, product-type dynamics, company-specific estimates, and concentration metrics are available in the full study. Readers seeking the granular intelligence required to build pricing models, structure procurement strategies, or assess competitive positioning can access the complete dataset and analysis through our research platform, where the full report provides the depth necessary to support confident, evidence-based decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Remicade (infliximab) Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide FRP Cooling Tower Market to Hit $1,323.23M in 2025, Grow at 5.48% CAGR to 2032
By pmarketresearch, 2026-09-17
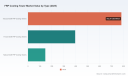
Navigating the Thermal Future: Strategic Intelligence for the Worldwide FRP Cooling Tower Market (2026-2032)
Executive Summary: The Imperative for Data-Driven Thermal Management
As industries globally pivot towards higher efficiency standards and stricter environmental compliance frameworks, the infrastructure supporting thermal regulation has become a critical focal point for capital expenditure planning. The Fiber Reinforced Plastic (FRP) cooling tower sector is not merely a component of industrial utility; it is a strategic lever for energy optimization, asset longevity, and operational resilience. Our latest comprehensive study, the Worldwide FRP Cooling Tower Market analysis, provides a granular look into the trajectory of this essential market through 2032. This article serves as a strategic preview, outlining the macroeconomic currents and competitive forces shaping the landscape, while highlighting the necessity of accessing detailed intelligence for precise decision-making.
For stakeholders operating in 2026, the margin between successful market positioning and operational lag often lies in the specificity of the data. General trends are insufficient for supply chain optimization, capacity expansion, or competitive benchmarking. This report bridges that gap, offering a robust framework for understanding how cooling infrastructure investment aligns with broader industrial goals in power generation, HVAC, and process industries.
Market Trajectory: Growth Dynamics and Core Drivers
The historical performance of the FRP cooling tower market indicates a steady upward trajectory, reflecting the increasing reliance on efficient heat exchange systems across heavy industry and commercial infrastructure. Between 2020 and 2025, the market demonstrated consistent revenue expansion, setting a strong foundation for the forecast period extending to 2032. The Compound Annual Growth Rate (CAGR) during the forecast horizon is projected at 5.48%, signaling sustained demand driven by industrialization in emerging economies and retrofitting activities in mature markets.
Revenue figures in USD Millions underscore the scale of the opportunity. Starting from a baseline in the early 2020s, the market revenue has climbed progressively, reaching new milestones by 2025. Looking forward, the valuation is expected to climb significantly, with projections indicating robust performance through the end of the decade. However, it is important to note that growth is not linear; it is subject to raw material volatility, regulatory shifts, and technological adoption rates. Our analysis dissects these variables to provide a nuanced view of potential revenue streams without relying on superficial aggregate numbers.
Segmentation Intelligence: Types, Applications, and Regional Nuances
Understanding the market requires a deep dive into how demand is distributed across different structural types and application verticals. The market is categorically divided by tower construction types, including Induced Draft, Forced Draft, and Natural Draft configurations. Each type offers distinct advantages regarding airflow management, energy consumption, and spatial requirements. Induced Draft units, for instance, dominate specific industrial scenarios where precise control over airflow is necessary, while Forced Draft systems are often favored for their compactness in constrained facilities. Natural Draft towers remain relevant for large-scale utility applications where longevity and low operational noise are prioritized. A detailed breakdown of the revenue contribution and growth potential of each type is essential for manufacturers determining their product mix strategy.
On the application front, the demand landscape is diverse. Power Generation remains a cornerstone consumer of cooling tower infrastructure, driven by the need for process cooling in thermal and nuclear facilities. HVAC applications represent a significant portion of the market, linking cooling tower demand to commercial construction rates and energy efficiency mandates in building management. Additionally, sectors such as Chemical and Petrochemical, Food and Beverage, and Oil and Gas contribute substantial volume to the market. Each vertical imposes unique operational stresses on cooling equipment, from corrosion resistance in chemical plants to hygiene standards in food processing. Our report details the specific requirements and spending patterns within each application segment, helping buyers align specifications with industry norms.
Geographically, the market exhibits varied intensity. Asia Pacific continues to be a hub of industrial activity and infrastructure development, reflecting in its significant share of market revenue. North America and Europe maintain steady demand driven by regulatory compliance and replacement cycles for aging infrastructure. Regions such as the Middle East and Africa, along with Latin America, present emerging opportunities tied to energy projects and industrial expansion. The regional analysis within our study goes beyond simple revenue splits to examine local supply chains, import/export dynamics, and region-specific regulatory hurdles that influence market entry and expansion strategies.
Competitive Landscape: Key Players and Strategic Positioning
The FRP cooling tower market is characterized by a mix of specialized manufacturers and broader industrial equipment providers. Market concentration levels indicate that while there is room for niche players, larger entities hold significant sway over pricing and technology standards. The competitive environment is fiercely focused on energy efficiency, durability, and certification compliance.
Several key companies define the current industry standards. Tower Tech, based in the United States, has positioned itself as a leader in modular FRP cooling towers utilizing pultruded FRP construction. Their focus on energy efficiency claims up to 40% less energy consumption, alongside water savings and critical certifications like FM Approvals for fire, storm, and seismic performance, sets a high bar for industrial and HVAC applications. Delta Cooling Towers, one of the oldest full-service fiberglass manufacturers in the US, emphasizes low maintenance and lightweight corrosion-resistant designs across multiple circular FRP models.
In the Asia Pacific region, particularly India, manufacturers like Gold Cooling Towers, World Cooling Towers, Perfect Cooling Towers, and Global Refrigeration & Equipments are strengthening the supply base. World Cooling Towers, for example, highlights ISO 9001:2015 certification and CTI standards compliance, offering energy-efficient belt-drive options. Perfect Cooling Towers expands the scope with dry cooling towers and various flow models, while Vincitore Edutechnologies caters to diverse sectors including power and petrochemical with induced and forced draft options. Chinese manufacturers such as Hebei Yiyang Environmental Protection Equipment also contribute to the global supply chain, focusing on FRP products for industrial applications.
Worldwide FRP Bridge Market
Competitive dynamics are further influenced by recent developments. For instance, Tower Tech highlighted industry-first fire certifications for factory-assembled FRP designs in early 2025. Meanwhile, semiconductor giant TSMC has continued rolling out high-efficiency cooling tower fans with FRP blades and epoxy coating, achieving significant electricity savings in fabs, illustrating cross-industry adoption of advanced cooling tech. These developments signal to stakeholders where technological differentiation is occurring.
Industry Dynamics: Materials, Efficiency, and Regulatory Pressures
The operational environment for FRP cooling towers is shaped by converging forces in raw materials, performance metrics, and regulatory compliance. Raw material costs fluctuate, impacting manufacturing economics. For example, glass fiber prices in the USA were observed around specific thresholds in early 2026, with comparable pricing in China. These costs are critical as fiberglass serves as a key reinforcement component in FRP construction. Furthermore, the global fiberglass market itself is projected to grow substantially over the next decade, driven by demand in composites for industrial applications. This macro trend suggests both supply availability and potential cost pressures that manufacturers must navigate.
Performance efficiency remains a primary driver for adoption. FRP cooling towers are noted to provide improvements in energy efficiency under high-humidity conditions compared to traditional materials. This aligns with broader industrial energy optimization goals, making FRP an attractive choice for facilities looking to reduce carbon footprints and operational costs.
Regulatory compliance is increasingly becoming a gatekeeper for market participation. FM Global approvals for fire, storm, and seismic performance are critical for FRP modular cooling towers in industrial settings to reduce loss exposure. Additionally, environmental permits for chemical facilities are increasingly explicit, referencing and regulating multiple FRP cooling tower cells for process brine cooling and emissions control. Such regulatory frameworks dictate not only what can be installed but also how it must be maintained and documented. Stakeholders must stay abreast of these evolving requirements to avoid compliance risks and ensure uninterrupted operations.
Strategic Value for 2026 Decision Makers
In the current economic climate, investing in market research is an investment in risk mitigation and strategic agility. The Worldwide FRP Cooling Tower Market report is designed to equip decision-makers with the intelligence needed to navigate these complexities. Whether you are a manufacturer considering capacity expansion, a procurement officer evaluating supplier reliability, or an investor assessing sector growth, the granular data contained in this study provides the necessary clarity.
Worldwide FRP Cooling Tower Market
The report offers actionable insights into supply chain vulnerabilities, emerging technological standards, and shifting demand centers. By understanding the interplay between raw material costs, regulatory updates, and regional growth rates, businesses can formulate strategies that are resilient to external shocks. The comprehensive segmentation analysis allows for precise targeting of high-growth niches, while the competitive profiling helps identify potential partners or threats in the value chain.
Conclusion: Accessing the Full Intelligence
The FRP cooling tower market is poised for continued evolution, driven by the dual engines of industrial growth and efficiency mandates. While this overview highlights the major trends and structural elements defining the sector, the full depth of the analysis contains the specific data points required to execute informed strategies. The nuances of revenue splits, detailed growth rates for specific segments, and in-depth company assessments are critical for moving from general awareness to specific action.
To leverage the complete potential of this intelligence for your organizational planning, we invite you to explore the full Worldwide FRP Cooling Tower Market research report. Access the detailed datasets, forecasts, and strategic recommendations that will define your competitive edge in the years leading up to 2032.
For detailed analysis of this topic, please visit the official page: Worldwide FRP Cooling Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Textile Staples Market Forecast to Grow 5.01% CAGR Through 2032
By pmarketresearch, 2026-09-17
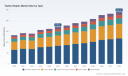
Navigating Volatility and Value: Strategic Intelligence for the Global Textile Staples Market (2026-2032)
The global textile staples market stands at a critical inflection point. As stakeholders navigate the period from 2026 to 2032, the interplay between shifting raw material costs, sustainability mandates, and evolving demand structures requires more than surface-level observation. It demands precise, forward-looking intelligence capable of informing capacity allocation, sourcing strategies, and competitive positioning. Our newly released Worldwide Textile Staples Market research report has been engineered specifically for this purpose, translating a decade of historical performance and multi-year forecasts into actionable strategic guidance for executives, investors, and supply chain leaders.
A Market Defined by Scale, Resilience, and Structural Transition
Drawing on a robust analytical framework covering the historical window of 2020 through 2025 and projecting forward to 2032, the report situates the textile staples industry within a trajectory of steady, compound growth. The sector, valued across its core revenue streams, has demonstrated remarkable resilience through cyclical demand fluctuations, supply chain disruptions, and macroeconomic uncertainty. Over the historical tracking period, total market revenue has progressed from approximately 132.45 billion USD in 2020 through a series of demand-driven and supply-constrained phases, reaching an estimated 170.16 billion USD by 2025. Forward projections indicate continued expansion, climbing to 177.04 billion USD in 2026 and advancing toward a projected 239.43 billion USD by 2032, underpinned by a forecasted compound annual growth rate of 5.01 percent.
These figures are not merely historical artifacts; they reflect the compounding effects of population-driven consumption, industrial textile integration, and the gradual maturation of regional manufacturing ecosystems. Yet the headline trajectory masks significant heterogeneity. Growth is neither uniform across product families nor evenly distributed geographically, and the report deliberately deconstructs these layers to reveal where structural advantages emerge and where margin compression risks intensify. Every forecast interval and baseline assumption is stress-tested against upstream feedstock dynamics, downstream end-use adoption curves, and policy-driven demand shifts.
What the Report Delivers: Operational Intelligence Beyond Top-Line Projections
The research is structured to move decisively beyond static sizing. It serves as a working toolkit for strategic planning, providing operational granularity where it matters most. Readers will encounter a comprehensive architecture of analysis that includes:
- A detailed segmentation mapping that isolates performance drivers across major staple fiber categories, application verticals, and regional supply-demand balances, enabling targeted market-entry and portfolio-allocation decisions
- Demand elasticity assessments that link textile staple consumption to downstream apparel, home furnishing, technical textile, and automotive-industrial cycles, highlighting inflection points where substitution patterns, premiumization trends, or specification upgrades alter volume trajectories
- Supply-side capacity and feedstock mapping that traces how upstream chemical intermediates, conversion economics, and regional production footprints influence short-term pricing behavior and long-term cost structures
- Competitive positioning frameworks that evaluate market share distribution, functional differentiation, and vertical integration strategies among leading global and regional producers
- Scenario-based forecasting modules that model how shifts in raw material pricing, sustainability regulation, trade flow reconfiguration, and technological adoption could reshape revenue streams and operating margins across the forecast horizon
Each analytical section is anchored in verifiable commercial realities and designed to be immediately usable in boardroom discussions, capital allocation reviews, and sourcing strategy workshops. The report does not simply describe the market; it equips decision-makers with the connective tissue between macro trends and tactical execution.
Competitive Architecture and the Emerging Battleground for Differentiation
The global textile staples landscape is shaped by a blend of integrated petrochemical giants, specialized fiber innovators, and regionally dominant manufacturers. The report provides an in-depth competitive profiling of the companies that are actively defining market standards, price signaling behavior, and technological baselines.
Indorama Ventures Public Company Limited, headquartered in Bangkok, Thailand, continues to operate as a major global producer of polyester staple fiber, spanning both virgin and recycled grades. Its significant capacity base across Asia and integrated operations position it as a central supplier to apparel, home textile, and nonwoven markets, while its strategic emphasis on recycled polyester staple fibers reflects a broader industry pivot toward circularity. Reliance Industries Limited, based in Mumbai, India, stands as a leading integrated polyester staple fiber producer with large-scale manufacturing operations that supply both virgin and recycled PSF for apparel and industrial applications, leveraging scale and domestic demand strength.
Toray Industries Inc., operating from Tokyo, Japan, brings a specialty orientation to the market, offering polyester staple fibers and other synthetic staples engineered for high-performance applications in apparel, automotive, and filtration textiles. Lenzing AG, headquartered in Lenzing, Austria, occupies a distinct premium niche as a premier producer of cellulosic viscose staple fibers derived from sustainable wood pulp, serving high-value apparel and nonwoven segments where brand equity and environmental credentials matter significantly. Grasim Industries Limited, part of the Aditya Birla Group and based in Mumbai, India, remains a key manufacturer of viscose staple fiber, with major production facilities supplying global blended yarn and fabric markets.
Alpek S.A.B. de C.V., headquartered in Monterrey, Mexico, produces polyester staple fiber through integrated PTA/PET operations, serving North American and international textile staple markets with a competitive cost and logistics advantage. Far Eastern New Century (FENC), based in Taipei, Taiwan, operates as a significant Asian producer of polyester staple fibers, including recycled grades, supplying apparel and home textile applications. Teijin Frontier Co., Ltd., also headquartered in Tokyo, Japan, supplies specialty synthetic staple fibers, including polyester, for technical textiles, automotive, and performance apparel. W. Barnet GmbH & Co. KG, based in Aachen, Germany, specializes in polyester and other synthetic staple fibers for nonwovens and technical textile applications, emphasizing functional performance. Sinopec Yizheng Chemical Fibre Company, located in Yizheng, China, operates as a large-scale producer of polyester and viscose staple fibers integrated with upstream petrochemical operations, linking feedstock economics directly to staple fiber output. Huvis Corporation, headquartered in Seoul, South Korea, manufactures polyester staple fibers for a broad range of textile staple end-uses, including filling and apparel.
Sewing Threads Market
This competitive mosaic is not static. The report evaluates how scale economics, product specialization, sustainability positioning, and regional integration create divergent strategic options. It further examines how these players interact within a market structure where the top three competitors collectively account for an estimated 18.4 percent of total revenue and the top five capture approximately 26.15 percent, indicating a moderately distributed landscape with room for both consolidation and niche differentiation.
2026 Industry Dynamics: Pricing Signals, Capacity Movements, and Regulation
The current operating environment is characterized by a series of interlinked developments that directly affect sourcing decisions, inventory planning, and capacity investment timing. Raw material pricing has emerged as a central variable. In China, polyester staple fiber prices have trended upward, supported by favorable upstream cost factors. More specifically, the domestic average market price for polyester staple fiber of standard specifications reached approximately 8,160 RMB per ton by mid-to-late March 2026, reflecting a notable intra-month increase driven by upstream PTA cost surges. Parallel movements have been observed in key feedstock markets, where PTA and MEG prices in India experienced sharp fluctuations in March 2026, rising before partially correcting. These upstream swings have direct pass-through implications for staple fiber margins and regional price competitiveness.
Viscose staple fiber markets have exhibited their own supply-driven dynamics. February 2026 pricing data recorded China-based viscose staple fibre prices at approximately 1,848 USD per metric ton and Indian prices at roughly 1,941 USD per metric ton, influenced by tight supply conditions and low inventories. These snapshots illustrate how regional supply tightness, inventory positioning, and mill operating rates can create short-term pricing divergence even within a broadly integrated global market. The report contextualizes these signals within longer-term cost curves, helping buyers and producers distinguish transient volatility from structural price shifts.
Capacity and product strategy developments further illustrate how participants are repositioning for the next cycle. In February 2026, Aksa Akrilik Kimya Sanayii A.S. commissioned an expanded production line, adding 30,000 metric tons of annual acrylic staple fiber capacity with advanced solvent recovery and energy efficiency upgrades tailored for technical textiles. Earlier, in January 2026, Pasupati Acrylon Limited announced capacity expansion at its Samba manufacturing facility in India, targeting increased acrylic staple fiber supply to domestic yarn spinning and knitwear clusters. On the product innovation side, Teijin Frontier Co., Ltd. launched THERMOFRONT in October 2025, a new master brand for sheet insulation that combines environmental responsibility with high thermal performance using specialty staple fibers. Indorama Ventures Public Company Limited expanded its dejaTM fiber and filament yarn portfolio in May 2025, enhancing sustainability offerings in recycled polyester staple fibers. Together, these moves highlight a market where capacity additions are increasingly linked to technical specifications, recycling credentials, and energy-efficient process design rather than volume alone.
Worldwide Textile Staples Market
Regulatory and sustainability pressures continue to reshape end-use preferences and technology adoption. In North America and Europe, sustainability mandates are favoring closed-loop and low-emission viscose staple fiber technologies amid broader textile environmental regulations. The report examines how these mandates influence procurement specifications, accelerate substitution toward certified cellulosic and recycled fibers, and reshape competitive advantages for manufacturers with advanced process capabilities and traceability systems.
Strategic Imperatives for 2026 Decision-Making
Translating these dynamics into executable strategy requires a clear understanding of where value is being created and where risk is accumulating. The report is designed to support several core strategic functions:
- Portfolio and sourcing alignment: Identifying which staple fiber categories and regional supply bases offer the most resilient cost profiles and specification flexibility under current feedstock and inventory conditions
- Capacity and investment timing: Evaluating how recent capacity expansions and product launches alter regional supply balances, and determining where new investment or partnership opportunities may emerge over the forecast period
- Competitive positioning: Understanding how leading players leverage vertical integration, specialty formulations, and sustainability credentials to protect margins and capture premium segments, and where fragmented segments remain open to focused entrants
- Regulatory and sustainability readiness: Mapping how evolving environmental mandates and consumer expectations influence demand for closed-loop, low-emission, and recycled staple fibers, and preparing procurement and product development roadmaps accordingly
By integrating historical performance, forward-looking projections, competitive profiling, and real-time market signals, the analysis enables organizations to convert uncertainty into structured decision-making. The goal is not to predict every fluctuation, but to establish a reliable framework for responding to them with discipline and speed.
Access the Complete Intelligence
The Worldwide Textile Staples Market research report offers a comprehensive, evidence-based view of the market's trajectory from 2026 through 2032, combining rigorous segmentation analysis, competitive dynamics, and scenario-ready forecasting into a single strategic asset. To explore the full dataset, regional breakdowns, application-level demand insights, and detailed company profiles that underpin the analysis presented here, please visit the source webpage to access the complete report. The publication is designed to serve as a foundational reference for procurement leaders, corporate strategists, investors, and industry analysts seeking to navigate the next phase of global textile staples market evolution with confidence and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Textile Staples Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pool & Spa Supplies Market Hits $18.45B in 2025, 5.24% CAGR to 2032
By pmarketresearch, 2026-09-17
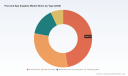
Navigating the Currents: Strategic Intelligence for the Global Pool and Spa Supplies Market 2026
The global pool and spa supplies industry stands at a critical inflection point as it moves through the 2026 calendar year. For executives, investors, and strategic planners, the difference between reactive management and proactive growth lies in the quality of intelligence available. Our latest Worldwide Pool and Spa Supplies Market research report is designed not merely as a data repository, but as a strategic compass for navigating the complex economic, regulatory, and competitive currents defining this sector. As the market continues to expand beyond its 2025 baseline of 18.45 billion USD, understanding the trajectory toward 2032 becomes essential for capital allocation, supply chain optimization, and product portfolio strategy.
This comprehensive analysis synthesizes historical performance data from 2020 through 2025 with forward-looking projections extending to 2032. The narrative that emerges is one of sustained growth tempered by significant macroeconomic headwinds. With a projected compound annual growth rate of 5.24 percent over the forecast period, the sector demonstrates resilience, yet the path to 26.38 billion USD by 2032 is not linear. Stakeholders must understand where value is consolidating, how regulatory shifts are reshaping cost structures, and which competitive maneuvers are defining market leadership in this mature yet evolving landscape.
Market Trajectory and Macro Economic Context
The historical window from 2020 to 2025 established a robust foundation for the industry. Revenue grew from 14.35 billion USD to 18.45 billion USD, reflecting a post-pandemic surge in residential outdoor living and a gradual stabilization of commercial hospitality sectors. The transition from 2025 into the forecast period suggests a continued upward momentum, with 2026 opening at 18.88 billion USD. However, market participants must recognize that aggregate top-line figures mask underlying volatility driven by input costs, tariff regimes, and shifting consumer spending patterns.
Worldwide Pool and Spa Supplies Market
Our forecast model projects the market will reach approximately 20.61 billion USD by 2027 and 21.32 billion USD by 2028, before accelerating toward 23.51 billion USD in 2029. It is crucial for decision-makers to note that growth trajectories are subject to external pressures. The market demonstrates a nuanced path, with slight consolidations observed in certain forecast years before resuming expansion toward the 26.05 billion USD mark in 2031 and the final 2032 projection. This volatility underscores the necessity of scenario planning rather than reliance on static growth assumptions.
Key macro drivers influencing this trajectory include the enduring preference for residential leisure assets and the ongoing rehabilitation of commercial aquatic facilities. However, the cost environment has shifted materially. Industry estimates suggest the U.S. pool service and maintenance segment alone reached 7.2 billion USD in 2025, with residential pool owners averaging around 1,700 USD in annual maintenance spend. This recurring expenditure supports a steady baseline demand for chemicals and maintenance tools, buffering the market against some volatility in equipment sales.
Regulatory Headwinds and Supply Chain Dynamics
No strategic assessment of the 2026 landscape is complete without addressing the profound impact of trade policy and raw material costs. The expansion of Section 232 tariffs in the United States during 2025 has subjected steel and aluminum content in derivative products to significant duties, reaching up to 50 percent for certain equipment categories including pumps, valves, and fittings. These measures, combined with reciprocal tariffs impacting imports from key trading partners, have fundamentally altered the cost calculus for manufacturers and distributors.
Further compounding these pressures, new tariffs on imported steel and aluminum at a 25 percent rate, alongside baseline duties on certain chemicals and components from China, are driving up manufacturing input costs. For domestic chlorine and pool chemical manufacturers reliant on imported inputs, these cost increases pose a direct threat to margins and retail pricing stability heading into the peak 2025-2026 pool season. The Pool and Hot Tub Alliance continues to advocate on these policy fronts, representing a broader 62 billion USD U.S. industry ecosystem, but the immediate operational reality for businesses is one of compressed margins and necessary price adjustments.
Pool Chemical Market
Strategic implications of these dynamics are multifaceted. Companies must evaluate their supplier diversification strategies, reconsider inventory positioning ahead of tariff implementations, and assess the elasticity of their customer base regarding price increases. Our report dissects these supply chain vulnerabilities to help organizations model the financial impact of continued regulatory friction and identify opportunities for localization or value engineering that can mitigate cost exposure.
Segmentation Landscape: Where Value Is Created
Understanding the architecture of the market is vital for targeting investment and sales efforts. The industry is broadly structured around equipment, consumables, and accessories, each exhibiting distinct growth profiles and sensitivity to economic cycles. In the equipment category, which represents a substantial portion of market revenue, innovation in energy efficiency and automation is driving replacement cycles. Water chemicals and treatment solutions form the recurring revenue backbone, closely tied to the aforementioned maintenance spend trends and regulatory standards around water quality and safety.
Maintenance tools and accessories, along with advanced cleaning systems, represent high-growth niches fueled by labor shortages in the service sector and consumer demand for convenience. The rise of robotic solutions and smart monitoring technologies is reshaping how owners interact with their aquatic assets, shifting value from purely mechanical components to integrated technology ecosystems. These segments are not growing in isolation; they are increasingly interdependent, with automation systems requiring compatible equipment and specific chemical regimes to function optimally.
Geographically, the market exhibits diverse maturity levels and growth potentials. North America remains a dominant revenue contributor, reflecting high pool penetration rates and a strong culture of residential outdoor living. Europe follows as a significant market, driven by tourism infrastructure and regulated public health standards. The Asia Pacific region presents a different dynamic, characterized by rapid urbanization and increasing disposable incomes fueling new installations. Latin America and the Middle East and Africa, while smaller in current revenue contribution, offer emerging opportunities tied to hospitality development and climate-specific demand. Our analysis provides the qualitative context and relative positioning needed to prioritize these regions without relying solely on historical volume metrics.
Competitive Arena: Strategic Positioning of Key Players
The competitive landscape is characterized by a mix of global equipment manufacturers, specialized technology providers, and massive distribution networks. Market concentration data indicates that the top three players hold approximately 32.4 percent of the market, while the top five control around 44.8 percent. This level of concentration suggests a competitive environment where scale advantages in distribution and manufacturing are significant, yet ample room remains for specialized innovators and regional leaders to capture value through differentiation.
Pentair plc continues to assert its position as a global leader, leveraging a comprehensive portfolio spanning pumps, filters, heaters, automation, and water treatment solutions across both residential and commercial segments. Their ability to integrate hardware with software services positions them well in a market increasingly driven by efficiency and connectivity. Similarly, Fluidra S.A. has built a formidable brand portfolio including Zodiac, Jandy, AstralPool, and Polaris, addressing everything from cleaning and filtration to heating and chemical systems. Their strategy emphasizes brand segmentation to address varied price points and consumer preferences across different geographies.
Hayward Holdings, Inc. remains a major force in the North American market, offering a wide array of equipment including pumps, filters, heaters, cleaners, lighting, and automation controls. Their focus on reliability and broad dealer networks reinforces their standing in the replacement and service markets. Maytronics Ltd. has carved a specialized niche through its Dolphin brand of robotic pool cleaners, capitalizing on the shift toward automated maintenance solutions that reduce labor dependency. This focus on high-value accessories allows them to punch above their weight in terms of margin contribution relative to volume.
In the residential infrastructure space, Latham Group, Inc. stands as the largest designer and manufacturer of in-ground residential pools, offering fiberglass pools, vinyl liners, and safety covers. Their recent milestone markings and product launches, including new plunge pools with integrated spas and partnerships in artistic swimming, signal a strategy of brand elevation and diversification into lifestyle experiences. Pool Corporation operates on the other side of the value chain as the largest wholesale distributor globally, wielding immense influence over product availability and pricing dynamics through its extensive sales centers and exclusive partnerships. Their recent showcases of new chemical systems and filter technologies highlight the importance of distribution partners in bringing innovation to market quickly.
Other notable participants include Jacuzzi Brands LLC with their premium positioning in spas and water features, Waterco Ltd. in filtration and treatment, and a growing cohort of manufacturers from China such as Emaux Water Technology and Guangdong Laswim, who are expanding their global footprint through cost-competitive equipment and accessories. Companies like Aqua Products Inc., S.R. Smith, Waterway Plastics, Speck Pumps, and Intex Recreation Corp. further diversify the landscape, addressing specific niches from robotic cleaners to above-ground solutions and specialized plumbing components. The interplay between these players defines pricing power, innovation speed, and channel access across the industry.
Innovation and Event Dynamics Shaping 2026
The flow of innovation in this sector is accelerated by trade shows and industry gatherings that serve as barometers for technological and market trends. The International Pool Spa Patio Expo in late 2025 demonstrated the industry's commitment to sustainability and product diversity, featuring participation from 40 countries and innovations across over 100 categories. Highlights included advancements in robotic cleaners, filtration efficiency, automation interfaces, and sustainability initiatives designed to support the 2026 buying cycle. Such events underscore the industry's pivot toward solutions that address energy consumption, water conservation, and operational ease.
Corporate activity in early 2026 further illustrates the dynamic nature of the market. Latham Group's recent activities, including the introduction of new deluxe plunge pools and strategic partnerships, reflect a focus on premiumization and brand visibility. Concurrently, Pool Corporation's retail summit showcased new chemical systems and exclusive partnerships with innovative solution providers, signaling a distributor-led push toward differentiated service offerings and proprietary product lines. These developments suggest that competitive advantage in 2026 will increasingly derive from the ability to bundle equipment with consumables, offer service-integrated solutions, and leverage exclusive channels to capture customer loyalty.
Strategic Imperatives for Decision Makers
As organizations prepare their strategies for the remainder of 2026 and beyond, several imperatives emerge from the current market intelligence. First, supply chain resilience must be prioritized. The tariff environment requires a rigorous review of sourcing strategies, with potential benefits to be gained from regionalizing production or securing long-term contracts that hedge against input cost volatility. Second, product portfolios should be evaluated through the lens of total cost of ownership for the end customer. As energy and water costs rise, solutions that deliver operational savings will command premium positioning and drive adoption.
Third, the recurring revenue potential in chemicals and maintenance tools should not be underestimated. With residential owners spending significantly on annual maintenance, businesses that can capture this recurring stream through subscription models, smart dosing systems, or service partnerships will build more predictable revenue bases. Fourth, competitive positioning requires clarity on where to compete. The market concentration data suggests that while leaders hold significant share, there are viable paths for specialists, particularly in high-growth segments like robotic cleaning and automation. Finally, geographic strategy must be nuanced. Growth rates and regulatory environments vary widely, and a one-size-fits-all approach risks misallocation of resources.
Conclusion: The Value of Deep Intelligence
The Worldwide Pool and Spa Supplies Market is evolving under a complex set of forces that demand more than superficial analysis. From the impact of trade policies on manufacturing costs to the shifting preferences of residential consumers and the strategic maneuvers of key competitors, the variables influencing success are numerous and interdependent. Our report provides the depth, granularity, and forward-looking perspective required to navigate this environment with confidence.
By accessing the full research, stakeholders will gain access to detailed segmentation analysis, precise regional forecasts, competitive benchmarking, and scenario models that quantify the impact of regulatory and economic variables. The insights contained within are designed to support critical decisions regarding market entry, product development, M&A targeting, and capacity planning. In a market projected to exceed 26 billion USD by 2032, the cost of incomplete intelligence is far greater than the investment in comprehensive analysis.
We invite you to explore the full report to unlock the specific data points, strategic frameworks, and actionable recommendations that will empower your organization to thrive in the dynamic world of pool and spa supplies. The currents are strong, but with the right intelligence, your strategy can not only withstand them but harness them for sustained growth.
For detailed analysis of this topic, please visit the official page: Worldwide Pool and Spa Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Grade Computer Market Hits $10.5B in 2025, Heading to $16.26B by 2032
By pmarketresearch, 2026-09-17
Global Resilience: Strategic Imperatives in the Worldwide Military Grade Computer Market (2026-2032)
The defense technology landscape has entered a decisive phase. As geopolitical tensions reshape procurement priorities and operational theaters demand greater computational sovereignty, the Worldwide Military Grade Computer Market stands at a critical inflection point. For executives navigating procurement, R&D allocation, and supply chain resilience, understanding the trajectory of this sector is no longer optional—it is foundational to strategic readiness.
Based on our latest comprehensive analysis, the market is projected to expand from a base of approximately $10,500 million in 2025 to $16,263.31 million by 2032, reflecting a compound annual growth rate of 6.45%. This growth is not merely a function of increased defense spending; it represents a structural transformation in how militaries compute, process data, and maintain operational continuity under extreme conditions. Our freshly released Worldwide Military Grade Computer Market report dissects this evolution with granular precision, offering decision-makers a roadmap through a sector where mission assurance and technological agility must coexist.
A Market Anchored in Operational Necessity
Military-grade computing differs fundamentally from commercial IT markets. Where enterprise buyers optimize for cost and convenience, defense procurement prioritizes survivability, interoperability, and compliance with rigorous environmental and electromagnetic standards. The market's trajectory reflects a dual engine: modernization of legacy platforms and deployment of next-generation capabilities across ground, airborne, and naval domains.
Between 2020 and 2025, cumulative expansion demonstrated resilience even amid supply chain disruptions and component scarcity. In 2020, the market stood at $7,681.76 million; by 2025, that figure reached $10,500.0 million. The forecast period ahead compounds this momentum, with annual valuations climbing steadily toward 2032. This sustained trajectory signals that defense organizations are treating rugged computing not as a tactical utility but as a strategic asset class—one that directly enables command, control, communications, computers, intelligence, surveillance, and reconnaissance (C4ISR) functions across contested environments.
Yet raw valuation figures only tell the opening chapter. The substance of this market lies in how spending is distributed across form factors, platforms, and geographies, and how competitive dynamics are being reshaped by technological standards, regulatory frameworks, and raw material availability. Our report provides the full map; what follows is a strategic preview of the terrain.
Segmentation Dynamics: Where Value Concentrates
The military computing ecosystem bifurcates across three analytical dimensions—type, platform, and region—each carrying distinct investment and risk implications. In terms of product architecture, embedded systems and rugged mobile platforms represent the dominant expenditure categories, reflecting a shift toward distributed, edge-capable hardware that can operate independently of stable infrastructure. Servers and storage units, while smaller in absolute terms, are gaining strategic relevance as data-intensive battlefield architectures demand localized processing for latency-sensitive decision loops. Wearable and handheld computers further illustrate how soldier-system digitization is pushing computing intelligence into the tactical edge.
Platform-wise, ground-based systems currently command the largest share of compute investment, supported by the breadth of land-vehicle modernization programs worldwide. Airborne applications follow closely, driven by avionics upgrades, unmanned aerial system payloads, and cockpit digitization initiatives that demand SWaP-optimized rugged hardware. Naval platforms round out the triad, where corrosive marine environments and electromagnetic compatibility requirements impose particularly stringent qualification barriers.
Geographically, the market displays pronounced concentration patterns. North America remains the most mature and investment-dense region, underpinned by sustained U.S. procurement cycles and export opportunities. Asia Pacific exhibits the strongest growth momentum, reflecting regional security reassessments and indigenous platform development. Europe maintains a stable, capability-focused demand profile, while Middle East & Africa and Latin America represent smaller but strategically significant deployments tied to specific modernization programs and allied cooperation frameworks.
Crucially, these segmentation dynamics are not static. They are being recalibrated by procurement policies, interoperability mandates, and supply chain constraints that differ dramatically across regions. The complete segmentation architecture—including revenue allocations, growth rate differentials, and sub-segment crossover effects—is mapped in detail within the report, where clients can identify which nodes of the value chain offer the highest strategic leverage for their specific business posture.
Competitive Architecture: Specialists, Integrators, and the Premium Tier
The competitive field in military-grade computing is characterized by a blend of incumbent defense electronics integrators, specialized rugged hardware manufacturers, and cross-over commercial entities that have adapted their platforms to defense specifications. Market concentration metrics indicate a moderately consolidated landscape, with the top three players holding approximately 34.2% of total market revenue and the top five accounting for roughly 51.85%. This structure suggests room for both established leaders and agile entrants who can meet qualification thresholds and deliver differentiated performance in harsh environments.
Several organizations define the sector's competitive contours. Curtiss-Wright Corporation exemplifies the mission-computer modernization playbook, with recent contract awards focused on MOSA-aligned computing architectures and platform upgrades for aircraft such as the U.S. Air Force C-17. Leonardo DRS has built a formidable position as a premier supplier of rugged military computer systems and displays, with sole-source battle management responsibilities and a portfolio exceeding 200,000 battle-proven systems qualified to military standards. General Dynamics and Northrop Grumman extend the integrator dimension, embedding rugged computing within broader mission systems and defense electronics portfolios for ground, naval, and airborne applications.
Private and multinational specialists further diversify the ecosystem. Getac Technology Corporation leverages MIL-STD-810H certified rugged platforms and COTS-aligned customization to serve defense applications in extreme conditions. Panasonic's Toughbook line brings commercial-hardened portability into field operations meeting military durability standards. Crystal Group, Mercury Systems, Kontron, and Extreme Engineering Solutions address embedded, VPX, and COM Express requirements, each emphasizing secure, size-weight-and-power-optimized architectures for mission-critical applications. MilDef Group, Neousys Technology, RuggON, and VarTech Systems contribute certified rugged computers and displays tuned to environmental and electromagnetic demands, while Wolf Advanced Technology, Acura Embedded Systems, Core Systems, and BAE Systems broaden the geographic and application footprint of rugged computing solutions across command, control, and connectivity environments. Elbit Systems Ltd. rounds out this cohort with integrated rugged computing and C4ISR offerings.
Recent developments underscore how product launches and program wins continuously reshape battlefield relevance. In March 2026, VersaLogic Corporation introduced the Raptor, an ultra-compact rugged embedded computer utilizing 13th Generation Intel processors designed for defense, edge, and uncrewed systems. The same month, Curtiss-Wright secured the selection to modernize U.S. Air Force C-17 mission computing with MOSA-aligned mission computers. In November 2025, Getac highlighted customized rugged military computer solutions in alignment with U.S. DoD COTS directions and MIL-STD-810H standards. These events are not isolated; they are indicators of the pace and precision with which competitive advantage is being contested.
The full competitive analysis in our report includes organizational profiles, strategic positioning, capability emphasis, and recent activity tracking across the key company set, enabling clients to benchmark partnership potential, competitive threats, and white-space opportunities with greater confidence.
Technology, Standards, and Regulatory Gravity
Military-grade computers do not succeed on performance alone. Qualification, certification, and regulatory compliance form the invisible scaffolding of this market. MIL-STD-810H remains the active standard for environmental testing, governing how rugged systems endure vibration, shock, temperature extremes, humidity, and particulate intrusion. Compliance with this standard, alongside electromagnetic compatibility requirements and platform-specific qualification processes, dictates not only product design but also time-to-field and qualification cost.
Parallel to technical standards, regulatory frameworks exert substantial influence over market behavior. The U.S. Department of Defense maintains ITAR and export control frameworks under 22 CFR Part 124 for defense services and technical data related to military computing systems. These controls shape global supply networks, partnership models, and cross-border technology transfer. They also create differentiated market access pathways, where companies with robust compliance infrastructure and secure manufacturing footprints enjoy structural advantages.
Supply-side risks add another layer of complexity. Recent years have highlighted the vulnerability of defense electronics to critical mineral and semiconductor-grade material disruptions. China's imposition of export controls and bans on gallium, germanium, and antimony—materials integral to semiconductors and defense electronics—has rippled through supply chains. The United States remains 100% import-reliant on gallium and approximately 85% reliant on antimony, with critical mineral shortages threatening defense production capacity for electronics including military computers. Rare earth elements face even broader concentration risks, with China dominating more than 90% of global processed rare earths used in military computing components. These realities are pushing procurement organizations and manufacturers alike toward diversification, stockpiling strategies, and qualification of alternative material pathways.
For companies operating in this space, regulatory and supply chain fluency is as important as engineering excellence. The report integrates these dynamics into market projections and competitive interpretation, helping clients anticipate how standards, controls, and raw material availability will shape pricing, lead times, and regional accessibility over the 2026-2032 horizon.
Strategic Reading for the 2026 Decision Cycle
As organizations finalize multi-year investment plans, three priorities emerge from the market's current trajectory:
- Platform modernization is cumulative, not cyclical. Mission computing refresh cycles span years, and programs winning today's milestones will influence demand well beyond the forecast window. Decision-makers should evaluate where their offerings align with active modernization campaigns across air, land, and sea domains.
- Certification is a moat, not a checkbox. MIL-STD compliance, ITAR readiness, and SWaP optimization are table stakes for credibility. Yet the differentiation point increasingly lies in how quickly and reliably these attributes can be demonstrated across product families and customization requests.
- Supply chain resilience has become a procurement criterion. With critical mineral concentration and export controls affecting component availability, buyers are factoring supplier geographic diversification, stock strategies, and alternative-material roadmaps into sourcing decisions. Companies that can articulate and deliver resilience will capture disproportionate influence in qualified vendor lists.
These themes are explored across every section of the report, from market sizing and segmentation to competitive profiling and regulatory context. The objective is not to present a static snapshot but to equip leadership teams with a decision-grade intelligence framework for 2026 and the years ahead.
Worldwide Military Grade Computer Market
Inside the Report: What Decision-Makers Will Gain
Our Worldwide Military Grade Computer Market study is structured to convert complex datasets into actionable strategic insight. Readers will find:
- A full historical and forecast market valuation series, anchored in consistent methodology and expressed in U.S. dollars, enabling revenue planning, benchmarking, and scenario modeling across the 2020-2025 historical window and the 2026-2032 forecast period.
- Detailed segmentation analysis across type, platform, and region, revealing where spending concentrates and how growth velocities differ by category and geography.
- Competitive landscape mapping with company profiles, capability summaries, and recent development tracking, providing a clear view of who is winning programs, launching products, and shaping standards adoption.
- Contextual analysis of regulatory frameworks, qualification standards, and raw material supply dynamics, integrated directly into market interpretation rather than treated as separate appendices.
- Identification of value-chain leverage points, enabling clients to prioritize market-entry pathways, partnership structures, and R&D investments in line with verified demand signals.
The report is intended for executives who require more than directional intuition. It is designed for teams that must justify capital allocation, align product roadmaps with procurement realities, and assess competitor moves against a quantified market baseline.
Access the Full Intelligence
The trajectory of the worldwide military grade computer market is being written now, in program offices, test ranges, and supply chain corridors around the world. To navigate it successfully, organizations need more than high-level estimates; they need precise segmentation, competitive granularity, and the strategic context to interpret change as it happens.
This article has outlined the strategic logic and the macro-scale direction of the market, but the full dataset, segmentation detail, company-level analysis, and scenario-ready forecasting are reserved for clients who engage directly with the complete study. The comprehensive intelligence—built to inform procurement strategy, market entry planning, and competitive positioning throughout 2026 and into 2032—is available through our official research portal.
For a market where mission assurance and technological adaptation determine outcomes, clarity is not a luxury. It is an operational requirement. We invite decision-makers to access the full report and equip their teams with the depth required to act decisively in the years ahead.
Embedded Computer Market
For detailed analysis of this topic, please visit the official page: Worldwide Military Grade Computer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial operations frequently depend on controlled fluid movement for cleaning, processing, water treatment, equipment maintenance, and production support. In these environments, a High Pressure Pump can provide the pressure generation required for applications where standard transfer equipment is insufficient. However, effective equipment selection involves much more than choosing a unit with a high pressure rating. Engineers and purchasing teams need to consider flow demand, operating conditions, fluid properties, duty cycles, installation requirements, and maintenance practices together.
Pressure and flow are closely connected but represent different operating requirements. A system may require substantial pressure while using a relatively controlled flow rate, while another application may prioritize higher fluid volume. Selecting equipment based only on one parameter can create an imbalance between the pump and the rest of the system. A suitable configuration should provide the required operating conditions while leaving an appropriate margin for normal variations in demand.
Pump design is another important consideration. Industrial pressure equipment can use different mechanical configurations depending on the intended application. Piston and plunger arrangements are commonly associated with applications requiring controlled delivery and elevated pressure. The number of pumping elements, stroke characteristics, drive arrangement, and valve configuration can all influence how fluid is delivered through the system. Consequently, a High Pressure Pump should be selected according to the complete operating profile rather than a single specification.
Material compatibility deserves careful attention when the pumped fluid is not ordinary clean water. Industrial liquids may contain chemicals, suspended particles, or other substances that can affect wetted components. Corrosion resistance, mechanical strength, seal compatibility, and temperature tolerance should therefore be considered during system planning. Choosing materials that correspond with actual operating conditions can help reduce premature deterioration and maintenance requirements.
Sealing technology is equally significant because pressure systems depend on effective containment of the working fluid. Seals and packing components are exposed to repeated pressure changes and mechanical movement. Their service life can depend on pressure, temperature, fluid characteristics, surface condition, alignment, and maintenance practices. Regular inspection can help operators identify leakage or abnormal wear at an early stage and take corrective action before a minor issue develops into a larger maintenance problem.
Industrial cleaning represents one of the most recognizable applications for pressure-generation equipment. High-pressure water can assist with removing dirt, residues, deposits, and other contaminants from machinery and industrial surfaces. The cleaning process depends on the relationship between pressure, flow, nozzle geometry, spray distance, water temperature, and the nature of the contamination. Using excessive pressure is not always appropriate because some surfaces or components may require controlled cleaning conditions.
In water treatment environments, pressure equipment may support filtration, flushing, circulation, and other process operations. Stable fluid delivery can be useful when downstream equipment requires predictable flow conditions. System designers may combine pumping equipment with valves, filters, pressure regulators, accumulators, and monitoring devices to create a more controlled process. The complete arrangement should be designed around the characteristics of the treatment process and the required operating range.
Maintenance planning has a direct influence on equipment availability. Operators can establish inspection routines covering lubrication, valves, seals, connections, hoses, pressure indicators, and other relevant components. Changes in operating noise, vibration, temperature, pressure behavior, or leakage may indicate that inspection is necessary. Preventive maintenance does not eliminate every possible failure, but it can provide a structured method for identifying wear and maintaining equipment in suitable operating condition.
Energy consumption should also be considered when designing a pressure system. Inefficient piping, unnecessary pressure losses, poor inlet conditions, and operation far from the intended duty point can increase energy demand. Properly sized piping and suitable system controls may help reduce avoidable losses. Keeping filters clean and maintaining mechanical components in appropriate condition can also contribute to consistent operation.
Installation is often overlooked during equipment selection, even though it can affect practical performance significantly. The pump should be installed on a stable foundation with appropriate alignment and sufficient access for inspection. Inlet piping should avoid unnecessary restrictions, while discharge connections should be arranged to manage pressure safely. Proper installation also makes routine maintenance easier and can support longer service intervals under appropriate operating conditions.
When evaluating pressure equipment for industrial use, organizations can benefit from reviewing application requirements before comparing individual models. Factors such as fluid type, required pressure, expected flow, operating frequency, environmental conditions, maintenance capability, and system configuration can help narrow the available options. A properly matched High Pressure Pump becomes part of a coordinated fluid-handling system rather than an independent component. Businesses seeking additional information about industrial pumping equipment can review https://www.triplex-plungerpump.com/product/pumps/ for product categories and application-oriented pumping solutions.